
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. PayPay Corporation (PAYP): Japanese Fintech Draws Strong Orders Amidst Global Uncertainties
- The platform dominates Japan’s mobile payments market with ~70% smartphone user adoption and 40 million monthly transacting users.
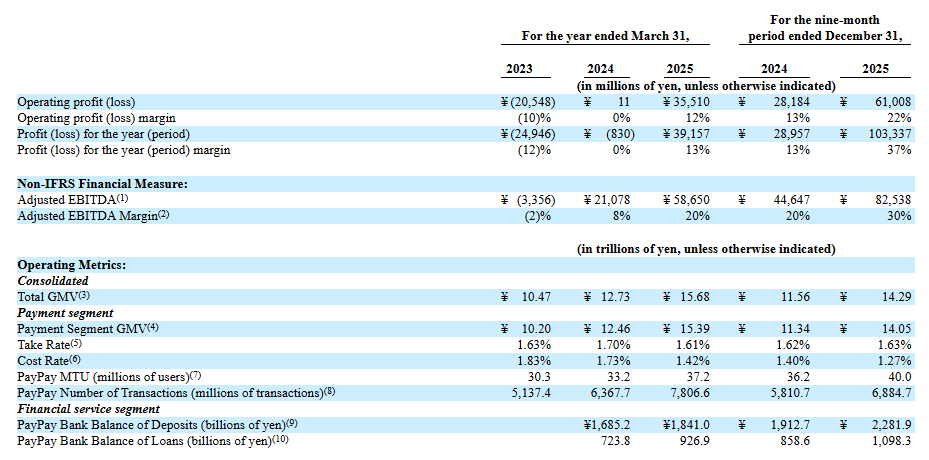
- Revenue reached ¥278B in the first nine months of FY2025 with ~30% EBITDA margins and steadily declining transaction costs.
- Premium valuation and volatile markets create execution risk despite strong fundamentals and $220M cornerstone demand from global investors.
2. MINIMAX-WP: Why Claws Matter?
- Stock price surge. MiniMax rose 20% on 9 March 2026 after Tencent announced internal testing of QClaw, bringing the total gain since our last note to over 35%.
- Claw ecosystem crystallises revenue opportunities. We trace the OpenClaw backstory, map seven ecosystem variants, and explain why Tencent’s QClaw is a distribution inflection point for MiniMax.
- Re-Rating potential. Consensus 2026E revenue implies only 5% MoM growth from the February ARR base. We assess why the street may be too conservative.
3. Aequitas: A/H Premiums and 27 Deals Performance-Better Returns, Some Premium & Coverage Correlation
- With over 27 A/H listings since the start of 2025, we look back at some of the trends from the recent listings.
- In this note, we will also talk about how the A/H premiums have moved since our last note in July 2025.
- Overall, A/H listings since 2025 have reversed the trend of past A/H listings not doing much in the near term, with a few exceptions.
4. [Japan Offering] Shimizu (1803) New Feb Global Index Entrant Sees March Crossholder Selloff
- Last month, Shimizu Corp (1803 JP) was included in the M _ _ _ Standard Index on 27 February. We had it in our QIPS months ago and published mid-month.
- We called it a sell/short when momentum turned (size determines that). It turned just after the inclusion. We had commented generically that more cross-holding sales were coming.
- Now a few large financial institutions are selling a total of 14.1mm shares. Some are clearing out. More will clear out later (banks have 2-3x that). Oof!
5. Aequitas: UI Boustead REIT IPO Trading – Decent Yield, Though Peers Have Been Correcting
- UI Boustead REIT (UIBREIT SP) (UBREIT), a logistics and industrial REIT, raised around US$767m in its Singapore IPO.
- UBREIT’s initial portfolio comprises 21 properties in Singapore and two properties in Japan. The total value of the IPO Portfolio is approximately S$1.9bn (US$1.5bn) as at 30 September 2025.
- We have looked at the company’s past performance and valuations, in our earlier notes. In this note we talk about the trading dynamics.
6. Delton Technology IPO: Higher Computational and Storage Requirement Will Drive Demand
- Delton Technology launched its Hongkong IPO aiming to raise around HK$3.3B (~ US$ 420M). It primarily develops, manufactures and sells customized PCBs for high performance servers and other computing applications.
- Delton Technology intends to use the IPO proceeds for funding expansion in Thailand & Guangzhou base, enhance R&D capabilities, pursue strategic partnerships/acquisitions etc.
- Given the prospects of AI, the requirement of data centers the demand for high-performance servers will be on the rise. The company will benefit from the growth momentum.
7. Aequitas: PayPay IPO Trading – Valuations Digestible, Sentiment Suffering
- PayPay (PAYP US), a payments and financial services platform, raised around US$880m in its US IPO after pricing below the range.
- PP operates a digital finance platform that serves as a payment solution for users and merchants, along with offering additional services.
- We have looked at its past performance and valuations in our earlier notes. In this note, we talk about the trading dynamics.
8. PayPay Corporation (PAYP): Discounted Japanese Fintech Debuts Strongly Despite Pricing Below Range
- PayPay priced 54.99M shares at $16, below its $17–$20 range, reflecting cautious pricing amid volatile markets and heightened geopolitical uncertainty.
- Shares opened strongly at $19 and closed at $18.16, remaining above issue all day despite a 1.5% decline in the broader market.
- Discounted pricing highlights valuation sensitivity in the IPO market as private companies transition to public markets during a challenging macro environment.
9. PayPay Opens 18.75% Above IPO Price as IPO Prophet Bear Signals Correctly Frame First-Day Trading
- PayPay Corp (PAYP) , a digital payments and fintech platform with deep penetration across Japan’s mobile payments ecosystem, began trading on March 12, 2026 with a mixed first session that ultimately shifted into a clear price discovery phase after the opening trade.
- Shares opened at $19.00, representing an 18.75% gain above the $16.00 IPO price.
- While the opening print reflected positive early demand from public market investors, no Bull signal was triggered during the pre-market indication period, which is the only window in which the IPO Prophet model can establish a bullish stance ahead of the opening trade.
10. Aequitas: Delton Technology A/H Listing – Wide A/H Premium and Cheaper than International Peers
- Delton Technology (1989 HK) is looking to raise up to US$420m in its upcoming Hong Kong IPO.
- It is a leading manufacturer of customized printed circuit boards (PCBs) for high performance servers and other computing applications.
- In this note, we examine the IPO dynamics, and look at the firm’s valuation.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Curator’s Cut: Seoul Searching Redux, APAC Placements Apace & More Private Markets Coverage
- Welcome to Curator’s Cut – a fortnightly roundup of standout themes from the 1,300+ insights published on Smartkarma.
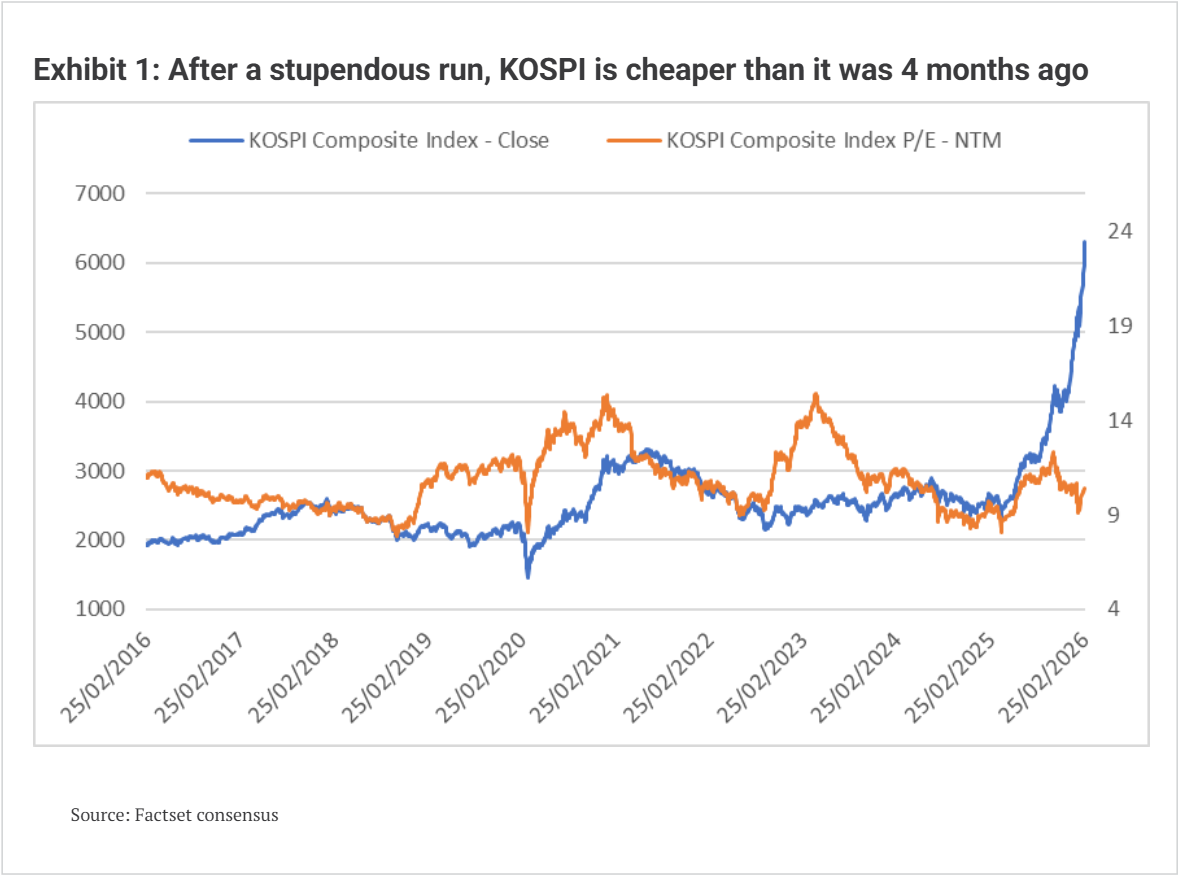
- In this cut, we examine why opportunities exist in Korea despite the record rally, look at the rush of shareholders trimming APAC stakes, and welcome coverage on 500+ private companies.
- Want to dig deeper? Comment or message with the themes you’d like to see highlighted next.
2. [Japan Offering] Japan Electronic Materials (6855 JP) – More Money for More Probe Cards
- With the huge boom in AI, the wafer, semiconductor, and SPE space has gone bonkers.Many stocks are up 5x, 10x, even 50x in the last months and years.
- Japan Electronic Materials (6855 JP) makes probe cards for wafer/IC testing. (between etch and dicing). The stock is up. Comps are up even more (and are expensive).
- 4 weeks ago, they revised up earnings, divs, and announced a new plant. Shares rose 100% in 3wks. Then a week ago, they announced an equity offering to fund it.
3. PayPay Sets Terms for ~$1.0B Nasdaq IPO as Profitable Japanese Fintech Scales Beyond $100B in GMV
- PayPay Corporation has set terms for its U.S.
- initial public offering and plans to list on the Nasdaq Global Select Market under the ticker PAYP .
- The company intends to offer 54,987,214 American Depositary Shares (ADSs) at a proposed price range of $ 17.00 to $20.00 per ADS.
4. UI Boustead REIT IPO: The Investment Case
- UI Boustead REIT (UIBREIT SP) invests in logistics, industrial, Hi-Specs industrial, and business space assets. It has launched an SGX IPO to raise proceeds up to US$770 million.
- The portfolio will comprise 23 Properties – with 21 leasehold Singapore Properties and two freehold Japan Properties.
- UI Boustead REIT offers an attractive value proposition, driven by a diversified portfolio, high occupancy rates, long portfolio WALE, growth opportunities, and debt headroom.
5. Aequitas: PayPay IPO – Thoughts on Valuations
- PayPay (PAYP US) (PP), a payments and financial services platform, is now looking to raise up to US$1.1bn in its upcoming US IPO.
- PP operates a digital finance platform that serves as a payment solution for users and merchants, along with offering additional services.
- We have looked at its past performance and undertaken a peer comparison in our earlier notes. In this note, we provide our thoughts on valuations.
6. PayPay IPO (PAYP US): Valuation Insights
- PayPay (PAYP US), Japan’s leading financial technology company, is seeking to raise about US$1.1 billion through a Nasdaq IPO.
- I previously discussed the IPO in PayPay IPO (PAYP US): The Investment Case.
- In this note, I present my forecasts and valuation. My analysis suggests that the IPO price range is attractive. The pricing date is 11 March.
7. Pre-IPO Estun Automation (PHIP Updates) – The Business, the Concerns and Thoughts on Valuation
- ESTUN’s core competitiveness is reflected in two dimensions: One is technological autonomy and vertical integration. The other is strong ability of “M&As + integration”. However, ESTUN’s profit performance is unsatisfactory.
- The lower limit of valuation is 1.2-1.5x P/S. The upper limit is 2-2.5x P/S. Based on 2025 forecast, market value is RMB6.1 billion-7.6 billion and RMB10.1 billion-12.7 billon respectively.
- Considering the current high financial risks and other challenges, a comfortable IPO valuation range could be between RMB8 billion and RMB11 billion. So, we think the IPO pricing is expensive.
8. Aequitas ECM Weekly (2 March 2026)- Toyota Motors, Nintendo, IBIDEN, Estun, PayPay, CleanMax
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, a number of deals were launched at the end of the week.
- On the placement front, there was a flurry of deals across the region, along with news of a possible large cross-shareholding unwind in Toyota Motor (7203 JP).
9. PayPay Corporation (PAYP): Japanese Fintech Sets Terms for IPO Amidst Broad Market Volatility
- PayPay Corporation plans to raise over $1 billion, offering 54.99M ADSs at $17–$20, implying an $11.7B–$13.7B market cap ahead of its March 12 debut.
- Approximately 56% of shares are primary, with SoftBank retaining 91.78% voting control post-IPO; cornerstone demand includes Qatar Holding, Visa, and ADIA for up to $220M.
- Strong profitability and scale support the story, but volatile markets and weak recent fintech IPO performance make execution a key near-term test.
10. UI Boustead REIT IPO – Diverse Asset Base
- Ui Boustead Reit (UIBREIT SP) (UBREIT), a logistics and industrial REIT, aims to raise up to US$767m in its Singapore IPO.
- UBREIT’s initial portfolio comprises 21 properties in Singapore and two properties in Japan. The total value of the IPO Portfolio is approximately S$1.9bn (US$1.5bn) as at 30 September 2025.
- In this note, we look at the company’s past performace.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
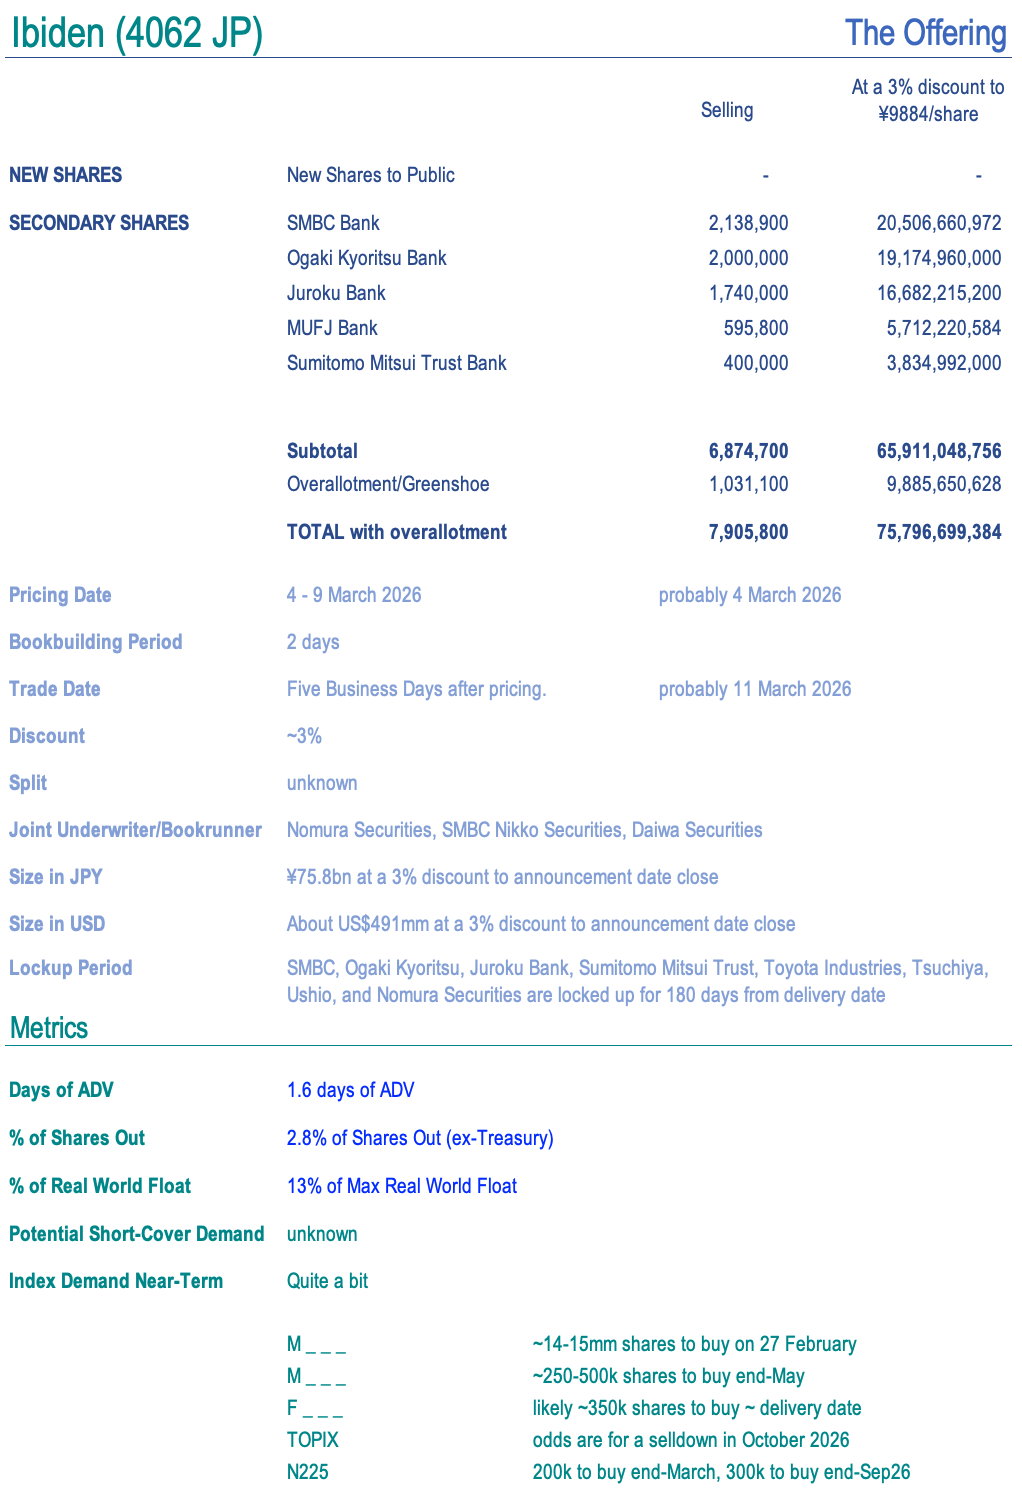
1. [Japan Offering] Five Banks Offer 3% of Ibiden (4062) After 400% 12mo Run into Friday’s Index Buy
- The stock is up 400% in a year. 3yr forward revenue consensus is up 20%, 3yr forward consensus earnings are up 50%. Multiples are therefore WAAAAY up.
- Today, five banks announced a partial selldown. They have more to go after, and there are lots of corporate crossholders not involved here.
- There is a big index upweight Friday after upweights in October and a Nikkei inclusion in November. HALF the September Max Real World Float has moved to Passive in 5mos.
2. PayPay IPO (PAYP US): The Investment Case
- PayPay (PAYP US), Japan’s leading financial technology company, is seeking to raise about US$2 billion through a Nasdaq IPO.
- In 2024, PayPay held an 64% share of Japan’s code-based payment market by transaction volume. It is a subsidiary of Softbank Group (9984 JP).
- The investment case rests on market leadership, the payment business’s robust transaction-driven growth, financial services’ increasing margin contribution, profitability, and a strong credit profile.
3. Nintendo (7974 JP): A US$2.1 Billion Secondary Offering
- Nintendo (7974 JP) has announced a secondary offering of 32.7 million shares (37.6 million including overallotment), worth around US$1.8 billion (US$2.1 billion including overallotment).
- There are four selling shareholders: Nomura Trust and Banking Co, Bank of Kyoto, DeNA (2432 JP), and Resona Bank.
- The offering as a percentage of outstanding shares and ADV is below average compared to recent large placements. A ToSTNeT-3 repurchase (up to JPY100 billion) will mitigate the impact.
4. Aequitas: PayPay Pre-IPO – The Positives – Dominant in the Payment Space
- PayPay (PAYP US) (PP), a Japanese payments and financial services platform, is looking to raise up to US$2bn in its upcoming US IPO.
- PP operates a digital finance platform that serves as a payment solution for users and merchants, along with offering additional services.
- In this note, we talk about the positive aspects of the deal.
5. Aequitas: Toyota Motors Cross-Shareholding – Possible US$19bn Unwind, Might Not Be Soon
- As per media reports Toyota Motor (7203 JP) (TMC) could be planning to unwind some of its US$19bn cross-shareholding by working with financial institutions.
- In our prior series of notes, we had looked at the cross-shareholding across a swathe of companies, the largest of which was Toyota Motors.
- In this note, we take a quick look at the possible shareholding unwind.
6. Aequitas: Capitaland India Trust Placement – Accretive Raising For Asset Construction
- Capitaland India Trust (CLINT SP) is looking to raise US$121m in a primary placement.
- The purpose is for financing of two office buildings in Bangalore, India.
- In this note, we will talk about the placement and run the deal through our ECM framework.
7. Cosmo Robotics IPO Valuation Analysis
- Our base case valuation of Cosmo Robotics is target price of 12,107 won per share (102% higher than the high end of the IPO price range).
- Our base case valuation of Cosmo Robotics is based on a P/S multiple of 45x our estimate sales of 8.8 billion won for the company in 2025.
- The P/S multiple of 45x is based on the average P/S multiple of the comps in 2025.
8. Aequitas: Ibiden Placement – Opportunistic Selldown as Shares Were up 8% Today
- A group of shareholders are looking to raise US$394m from selling their respective stakes in Ibiden Co Ltd (4062 JP).
- The deal is another cross-shareholding unwind, which has been an ongoing narrative in Japan over the past 1-2 years.
- In this note, we will talk about the placement and run the deal through our ECM framework.
9. Wuxi Lead Intelligent Equipment – The Concerns On Fundamentals and the Valuation Outlook
- Investors are concerned about whether this high growth in 2025 represents a temporary rebound in industry or a sustainable trend. The concern on fundamentals directly suppressed the stock price performance.
- The IPO pricing of HK$45.8/share is supported by core strength and business model, but it does not leave sufficient safety margin to hedge against short-term market pessimism towards cyclical stocks.
- Given the current market attitude towards new energy equipment, HK$35-42/share may represent a more solid bottom area.Share price can easily break through IPO pricing when WUXI LEAD fulfill high-growth commitment.
10. HPSP Placement: Yet Another Opportunistic Selldown by Crescendo Equity Partners
- Crescendo Equity Partners is looking to raise ~US$225m via a secondary placement of its shares in HPSP (403870 KS) .
- This comes after a prior selldown last month and before their 90 days lockup.
- In this note, we will talk about the placement and run the deal through our ECM framework.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
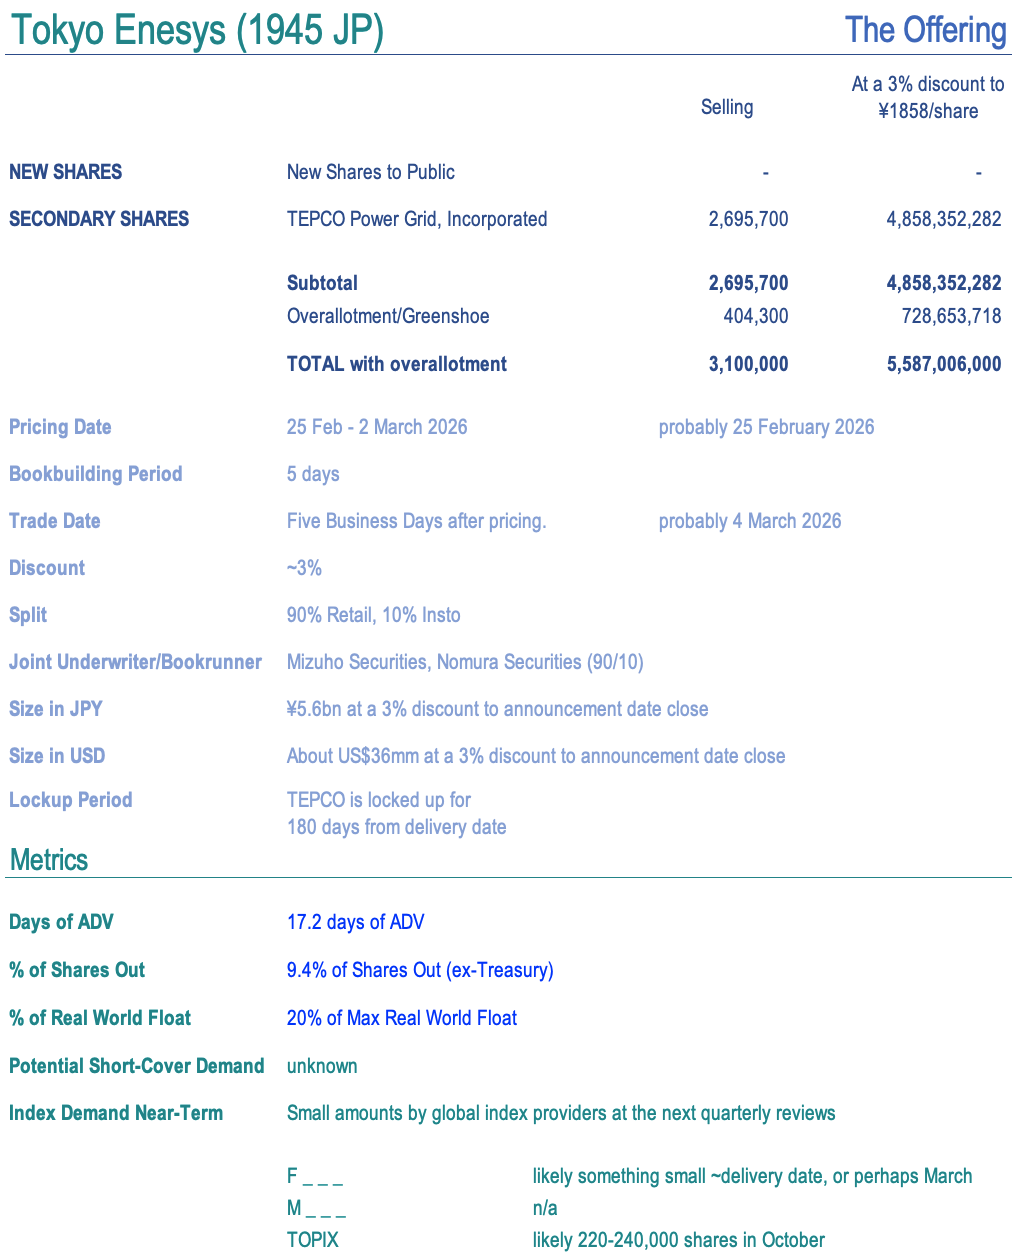
1. [Japan ECM] TEPCO Selling Tokyo Enesys (1945 JP) Shares – Shouldn’t Be Surprising
- Yesterday after the close, Tokyo Electric Power Co (9501 JP) and Tokyo Energy & Systems (1945 JP) announced TEPCO would offer up to 3.1mm shares (including greenshoe) in Enesys.
- This is not enormous. It is about 9% of shares out. TEPCO will no longer treat it as an equity affiliate and it somewhat frees up the register.
- This was better done as a tender offer buyback. Tokyo Enesys is cheap as a capital construct but its equity is tied up where it shouldn’t be.
2. Aequitas ECM Weekly (16 February 2026)- Montage, Axera, Wuxi Lead, Woer, Top Toy, Anker, PhonePe
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, after a stellar listing for Montage, other listings during the week didn’t do much.
- On the placement front, we had a look at a few of the upcomng lockup expiries.
3. Aequitas: Nexchip Semiconductor A/H Listing – Recently Listed A-Shares, Now Raising Again
- Nexchip Semiconductor (688249 CH), aims to raise up to US$550m in its H-share listing.
- It is a pure-play 12-inch wafer foundry providing comprehensive wafer fabrication services across mainstream technology nodes ranging from 150nm to 40nm, while steadily advancing 28nm platforms.
- In this note, we look at its past performance and other deal dynamics that might impact the listing.
4. Pre-IPO WinHealth International Holding- A BD-Driven Model May Not Guarantee Sustainable High Growth
- By establishing a multi-engine BD model of “M&A+licensing cooperation+CSO”, WinHealth’s ability to identify and acquire innovative drugs and other high-quality assets with significant commercial potential is effectively enhanced.
- Based on our forecast, high growth in 2025 is driven by the Kyowa Kyrin China Acquisition.In 2026-2027, Kapruvia is expected to drive the growth of WinHealth.However, revenue growth gradually declined.
- Valuation should be lower than pure innovative drug companies (e.g. Innovent, Akeso, Kelun Bio, etc.), and CMS who has similar business model but more mature system and higher profit margin.
5. Aequitas: Fractal Analytics IPO Trading – Lacklustre Demand
- Fractal Analytics Ltd (2453623D IN) raised US$315m in its India IPO.
- Fractal Analytics is an enterprise artificial intelligence (AI) company which supports large global enterprises with data-driven insights and assists them in their decision making through its end-to-end AI solutions.
- We have looked at the company’s past performance and valuations in our previous notes. In this note, we will talk about the trading dynamics.
6. Aequitas: Shiprocket Pre-IPO- Business Expansion Through Targeted Acquisitions
- Shiprocket (1087190D IN) is looking to raise about US$253m in its upcoming India IPO. It is a technology platform helping small-medium businesses and large retailers in India carry e-commerce transactions.
- It supports merchants by simplifying key processes such as logistics, checkout, payments, order fulfilment, and cross-border trade, allowing them to sell both online and offline efficiently and at scale.
- In this note, we talk about the company’s historical performance.
7. Aequitas: Contact Energy Placement – Large Deal to Digest but Guidance Has Been Increased
- Contact Energy (CEN NZ) is looking to raise US$272 in its primary offering.
- The company plans to use the proceeds for further investments into renewable energy and advance the Contact31+ strategy.
- In this note, we will talk about the placement and run the deal through our ECM framework.
8. Aequitas: MeiG Smart Technology A/H Listing – PHIP Updates and Thoughts on A/H Premium
- MeiG Smart Technology Co Ltd (002881 CH), a provider of wireless communication modules and solutions, aims to raise around US$150m in its H-share listing.
- MeiG is a provider of wireless communication modules and solutions, with a product portfolio consisting of (1) smart modules and (2) data transmission modules.
- In this note, we talk about the recent updates on the company’s past performances, and likely A/H premium.
9. Aequitas: Marri Retail Limited Pre IPO Tearsheet
- Marri Retail Limited (1489143D IN) plans to raise US$221m via a mix of fresh issue & OFS in upcoming India IPO. The deal is run by IIFL, Nuvama, Motilal Oswal.
- MRL is an apparel and jewellery retailer offering products across premium, mid-premium, and value segments. It operates 34 stores spanning 26 districts across Telangana, Andhra Pradesh, Karnataka, and Maharashtra.
- MRL operates its stores under The Chennai Shopping Mall, JC Mall, J.C. Brothers, and Jeans Corner brands in apparel category, and The Chennai Shopping Mall Jewellers in jewellery category.
10. PayPay Corporation (PAYP): Peeking at the IPO Prospectus of a Japanese Fintech
- PayPay Corporation filed for a U.S. IPO on February 12, targeting a potential March debut, backed by SoftBank and a top-tier global underwriting syndicate.
- With 72 million registered users and ¥15.39 trillion in FY2025 GMV, PayPay leads Japan’s cashless market with over 20% sustained annual transaction growth.
- Expansion into banking and securities, improving profitability, and strong eKYC penetration position PayPay as a scaled, integrated digital finance ecosystem amid accelerating cashless adoption.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
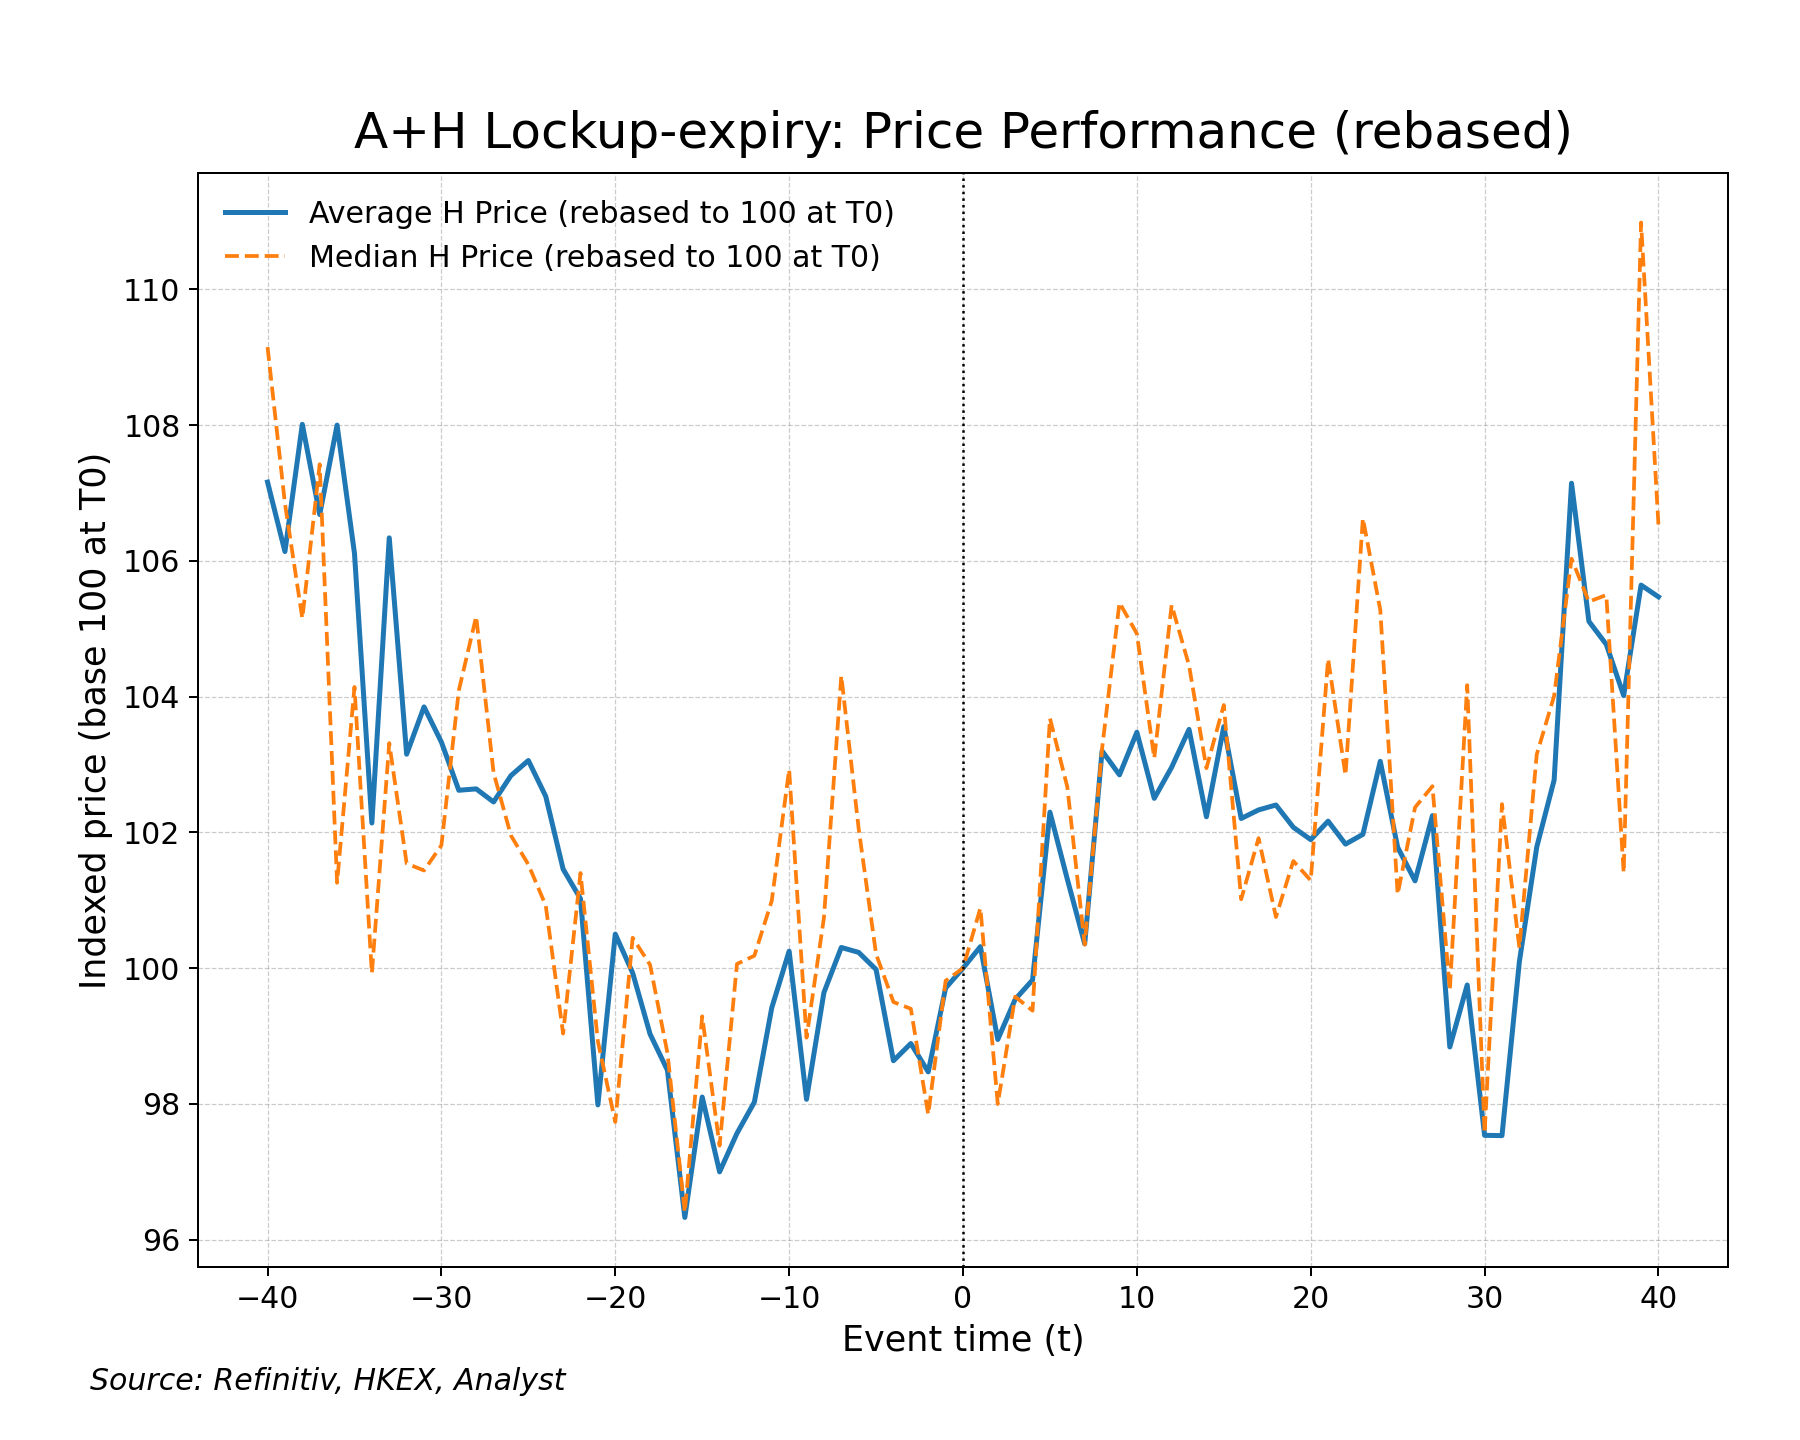
1. HK A+H IPO 2025 Cornerstone Lock-Up Expiry: Price and Liquidity Evidences
- We examine H-share trading behavior around the six-month cornerstone lock-up expiry for A+H listings since 2025, assessing whether these events create systematic price pressure or primarily affect liquidity.
- We align each stock around its expiry date (T0) and analyze price and trading volume, incorporating both market-adjusted returns and a measure of overhang intensity relative to typical liquidity.
- Elevated trading activity emerges around expiry, but we find no consistent aggregate post-expiry underperformance; overhang intensity appears more linked to liquidity shifts than directional price moves.
2. Pre-IPO Wuxi Lead Intelligent Equipment (A/H Listing) – The Core Strength and Thoughts on Valuation
- The “comprehensive technical expertise+ whole-line delivery capability+global top-tier customer ecosystem” forms unique barrier of WUXI LEAD. The competitive logic has evolved from “equipment cost-effectiveness” to “technological gap” and “solution capability”.
- The IPO pricing is HK$45.8/share, with market value of HK$76 billion (or RMB67.5 billion). Based on the net profit forecast of 2025, 2026, 2027, P/E is 42.2x, 29.4x, 22.5x, respectively.
- 35-40x P/E is acceptable range. The IPO pricing may have partially reflected the expectations for future growth. Considering WUXI LEAD’s growth certainty is higher, it can enjoy certain valuation premium.
3. Aequitas ECM Weekly (9 February 2026)- Eastroc, Muyuan, Han’s, Montage, Axera, Woer, Fractal
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, most of the recent listings have managed to hold on to the deal price.
- On the placement front, there weren’t many deals over the past week.
4. Aequitas: Montage Technology A/H Trading – Highest Insti Coverage so Far
- Montage Technology (688008 CH) (MT), a provider of memory interface chips and interconnect chips, raised around US$1bn in its H-share listing
- MT’s product portfolio, mainly comprises memory interface chips and interconnect chips, addresses interconnect bottlenecks while enhancing data rate/bandwidth, reliability, and power efficiency, as per the company.
- We have looked at the past performance and likely A/H premium in our previous note. In this note, we talk about the trading dynamics.
5. K Bank IPO Book Building Results Analysis
- K Bank finalized its IPO price at 8,300 won, which is at the low end of the IPO price range. The demand ratio for the IPO was 199 to 1.
- The 12.4% shares that are under lock-up periods is relatively low and this suggests a bearish sign.
- Our base case valuation of K Bank is target price of 11,986 won per share, which is 44% higher than the IPO price of 8,300 won.
6. IPO Rating: Clear Street Group, Inc.
- ✅ IPO PROPHET RATING: 8.1/10 🏦 Deal Quality & Underwriters: 8.9/10 Clear Street Group has filed to list on the Nasdaq under the ticker CLRS via a 23.81 million share IPO at a price range of $40.00 to $44.00 per share, implying gross proceeds of approximately $1.0 billion at the midpoint.
- The offering is anchored by an elite underwriting group, substantial float for institutional participation, and a differentiated business model that combines execution, clearing, financing, and related services for sophisticated trading clients.
- Clear Street’s IPO is being executed as a true institutional allocation rather than a momentum-driven distribution.
7. Aequitas: Anker Innovations Technology A/H Listing – Building a Global Brand
- Anker Innovations Technology (300866 CH) (AIT), a global consumer electronics company, aims to raise around US$1bn in its H-share listing.
- AIT sells products across three major product lines — smart charging and power storage, smart home and innovation, and smart audio and video.
- In this note, we look at its past performance and other deal dynamics that might impact the listing.
8. Aequitas: Huaqin A/H Listing – Had Just Listed Three Years Ago; Margins Remain Volatile
- Huaqin Technology (603296 CH) , aims to raise up to US$800m in its H-share listing.
- It is a global leading, technology-driven smart product platform providing end-to-end solutions across the entire value chain, including R&D, design, manufacturing, and operations.
- In this note, we look at its past performance and other deal dynamics that might impact the listing.
9. Aequitas: Top Toy Pre-IPO – Fast Growing but Listing to Capture Hype on Popmart
- TOP TOY International Group (TOYTOY HK) is looking to raise around US$300m in its upcoming Hong Kong IPO.
- It operates as China’s largest and fastest-growing pop toy collection brand.
- In this note, we look at the firm’s past performance.
10. Aequitas: Wuxi Lead A/H Trading – Weak Retail, Okish Institutional Demand
- Wuxi Lead Intelligent Equipmen (300450 CH), raised around US$725m in its H-share listing.
- WLIE is a global platform-based intelligent equipment enterprise, offering intelligent equipment and solutions to a wide range of emerging and high-end manufacturing industries.
- We have looked at the past performance and likely A/H premium in our previous note. In this note, we talk about the trading dynamics.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Muyuan Foods Hong Kong IPO Valuation Analysis
- Our base case valuation of Muyuan Foods Co (2714 HK) is implied market cap of HK$368 billion post IPO which is 24% higher than HK$297 billion at HK$39 per share.
- Our base case valuation of Muyuan Foods is based on P/E of 12.9x our estimated net profit of RMB25.3 billion in 2027.
- Our target P/E multiple of 12.9x is 20% higher than the comps’ average P/E multiple in 2027.
2. Montage Technology (6809 HK) IPO: Decent Upside Potential
- As a global leader in fabless IC design, focusing on interconnect solutions for cloud computing and AI infrastructure, Montage Technology (6809 HK)‘s 3-year EPS CAGR will reach 43.2%.
- We assess a fair price at HK$147.4, or 45.8x FY26 PER, a 20% premium over Rambus (RMBS US), the third-largest player globally.
- This represents a 37.9% upside, also putting it in line with the average of 28% discount of the H-share IPOs to A-shares since 2025.
3. Shenzhen Woer Heat A/H Listing: Copper Cable Player for AIDC Buildout
- Shenzhen Woer Heat Shrinkable Mat (002130 CH), aims to raise around US$400m in its H-share listing.
- It is a global manufacturer primarily engaged in sales of high-speed data communication and electrical power transmission products, with a core focus on heat-shrinkable materials and telecoms cables.
- In this note, we look at its past performance and other deal dynamics that might impact the listing.
4. Muyuan Foods (2714.HK) – Thoughts on IPO Pricing and Valuation Outlook
- MUYUAN plans to issue 274 million shares at a maximum price of HK$39/share. If based on net profit forecast of 2025, 2026, 2027, P/E would be 11x, 9.5x, 7.7x, respectively.
- Reasonable valuation of MUYUAN-A share and MUYUAN-H share would be higher than peers such as Wens Foodstuff (P/E of 12.9x by Jan.30), WH Group (P/E of 9x by Jan.30).
- If industry average valuation is used as the benchmark, based on 2026 forecast, the IPO pricing leaves decent room for stock price increases for both MUYUAN A and H share.
5. Shin Etsu Chemical (4063 JP): The Current Playbook
- Since the announcement of the US$1.0 billion secondary offering, Shin Etsu Chemical (4063 JP)’s shares have declined 6.3% to the undisturbed price of JPY5,476 per share (27 January).
- It is instructive to look at recent large Japanese placements to understand the potential trading pattern. Shin Etsu’s share decline is lower than the median of recent large placements.
- The offering will likely be priced on 4 February. The average large Japanese placement tends to generate positive returns.
6. Muyuan Foods Hong Kong IPO Preview
- Muyuan Foods Co (2714 HK) is getting ready to complete its Hong Kong IPO on 6 February 2026. This listing involves an offering of 273.95 million H shares.
- The offer price is capped at HK$39 per share. The offering involves raising approximately HK$10.7 billion ($1.4 billion USD).
- Muyuan Foods is the largest company globally in the hog farming industry by both production capacity and hog sales volume.
7. Muyuan Foods H Share Listing (2714 HK): Trading Debut
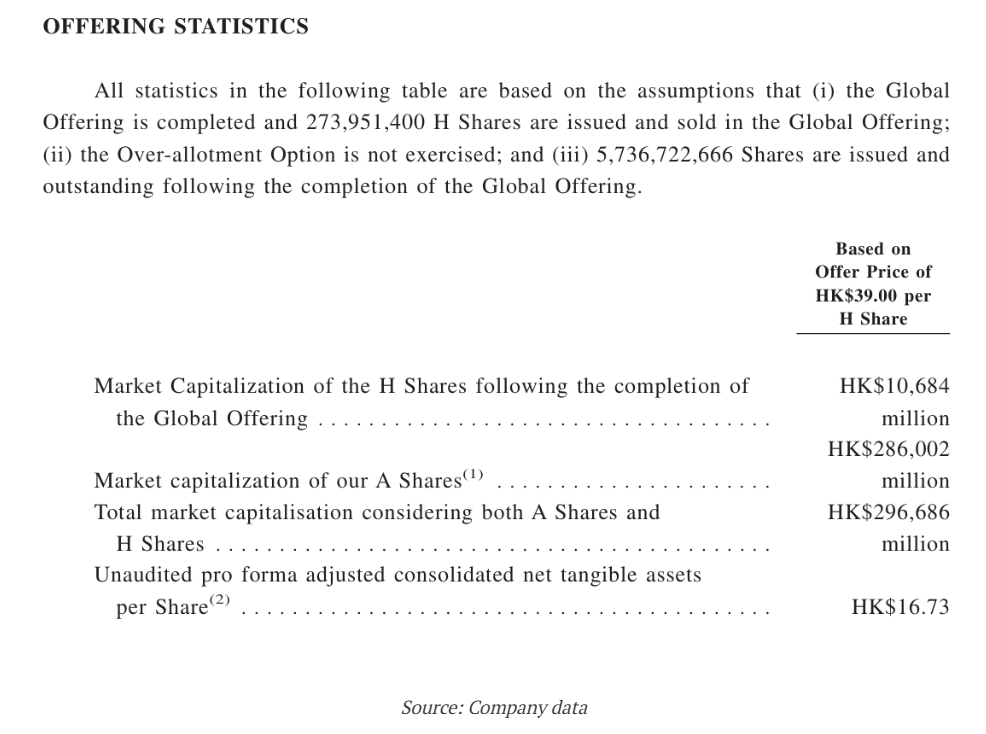
- Muyuan Foods Co (2714 HK) priced its H Share at HK$39 to raise HK$10,684 million (US$1.4 billion) in gross proceeds. The H Share will be listed tomorrow.
- I discussed the H Share listing in Muyuan Foods H Share Listing: The Investment Case and Muyuan Foods H Share Listing (2714 HK): Valuation Insights.
- Muyuan’s international and retail oversubscription rates were below the median of recent large AH listings. The AH discount remains attractive.
8. Montage Technology Hong Kong IPO Preview
- Montage Technology (6809 HK) is getting ready to complete its Hong Kong IPO next week (first date of trading is scheduled for 9 February).
- Shares were priced at HK$106.89, the maximum of the marketing range, raising HK$7.04 billion (US$901 million). This values the company at roughly HK$180.36 billion (US$23 billion).
- Montage is one of only three global suppliers of DDR5 memory interface chips (alongside Renesas and Rambus), holding a 36.8% market share.
9. Aequitas: Wuxi Lead Intelligent Equipment A/H Listing – Quality Asset, Slightly Tight Pricing
- Wuxi Lead Intelligent Equipmen (300450 CH), aims to raise around US$550m in its H-share listing.
- WLIE is a global platform-based intelligent equipment enterprise, offering intelligent equipment and solutions to a wide range of emerging and high-end manufacturing industries.
- We have looked at the company’s past performance in our previous note. In this note, we talk about the pricing.
10. Aequitas: Lingyi ITech A/H Listing – More Smartphones than AI, but Has Robotics
- Lingyi iTech Guangdong (002600 CH, LIT), an intelligent manufacturing platform, aims to raise around US$1bn in its H-share listing.
- LIT offers a full range of development and manufacturing capabilities that cover core materials, high-precision functional components, modules and assembled systems for diverse end products.
- In this note, we look at its past performance and other deal dynamics that might impact the listing.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
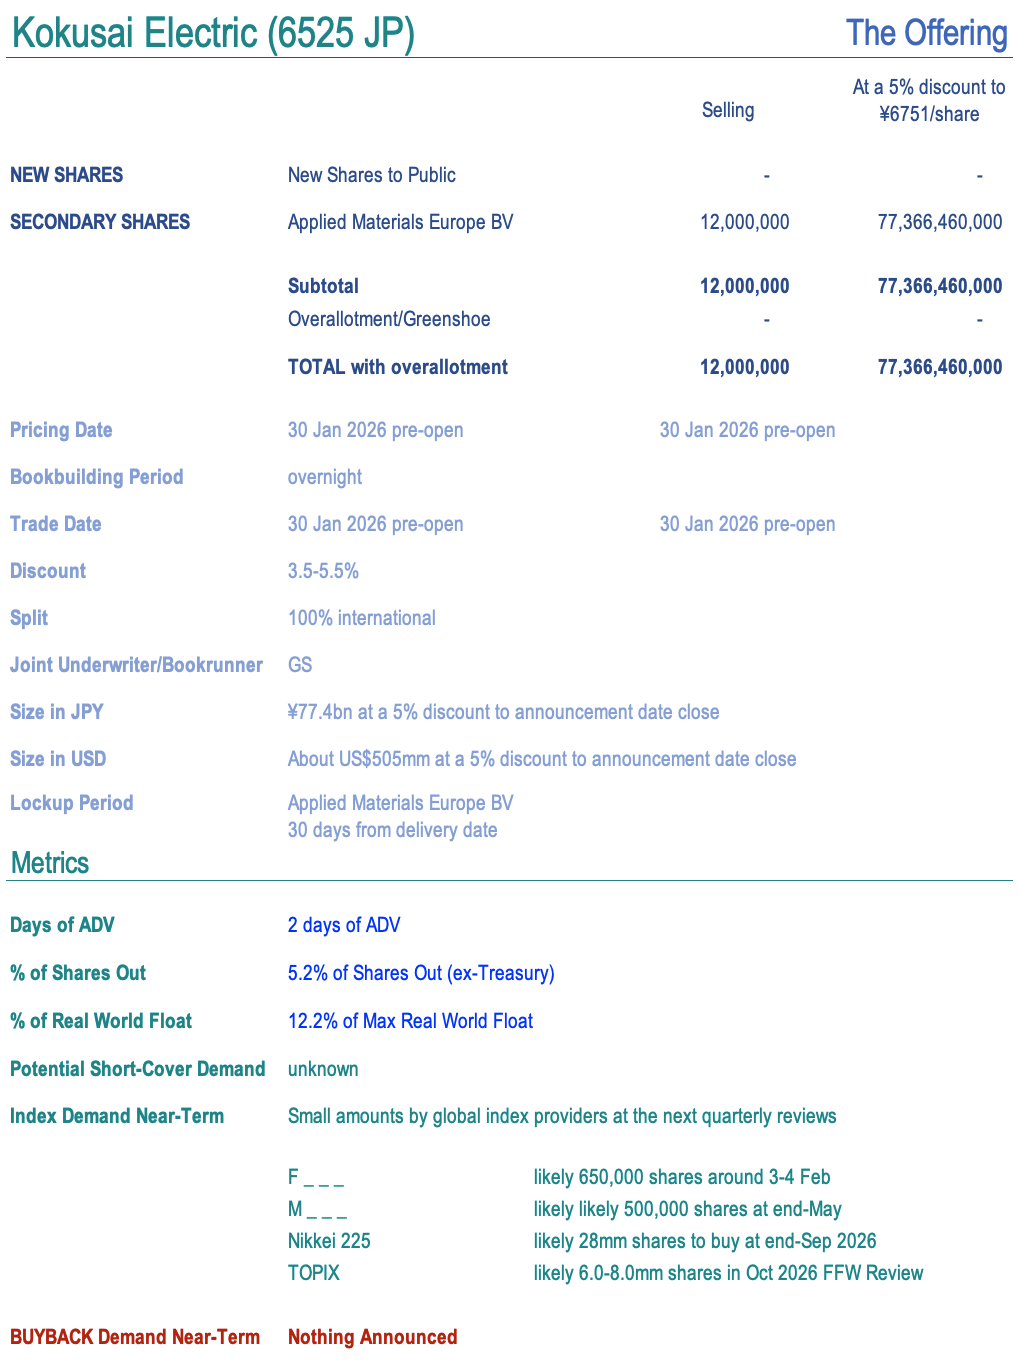
1. [Japan ECM] Kokusai Elec (6525) – ANOTHER Applied Materials Selldown
- In early October, Applied Materials (AMAT US) sold down a US$330mm stake in Kokusai Electric (6525 JP). Today post-close they return for another 12mm shares.
- The last two offerings went well. This one feels a bit more like the first, not the second and third, but it’s a different world now.
- There are some index upweights in the next couple of months. There are likely some big ones 8-9mos down the line.
2. [Japan ECM] Shin-Etsu Chem (4063) Secondary Selldown by Financial Crossholders
- Today after the close, Shin Etsu Chemical (4063 JP) announced a selldown of 27.23mm shares (including greenshoe) by eight crossholders.
- The offering is US$900mm or so if the stock falls a bit. That is 4.2x ADV and 3% of Max Real World Float. There is minimal index impact.
- But there is a follow-on buyback. Earnings has been less salutary than the guidance was but the buyback continues apace, and this offering is 70% covered by end-April.
3. [Japan ECM] TEPCO Selling Kandenko (1942) Shares – Earnings Surprised But Narrative Violation?
- Today during the day, Kandenko Co Ltd (1942 JP) announced a sharp upward revision to its full-year guidance. Revs+4.6%, OP+27%, NP +32%. It was good. The stock popped.
- After the close, major owner (46%) Tokyo Electric Power Co (9501 JP) announced a selldown of 12.8% of shares out or 23x ADV.
- There is a buyback to cover not quite a quarter of it, and index buying will help with another 10%, but the narrative may have changed here.
4. Shin Etsu Chemical (4063 JP): A US$1.0 Billion Secondary Offering
- Shin Etsu Chemical (4063 JP) has announced a secondary offering of up to 23.7 million shares (27.2 million including overallotment), worth around US$0.8 billion (US$1.0 billion including overallotment).
- The goal of the secondary offering seems to be to facilitate the exits of several shareholders and improve liquidity.
- The offering as a percentage of outstanding shares and ADV is small compared to recent large placements. An ongoing JPY100 billion share buyback will further mitigate the impact.
5. Aequitas: Kokusai Electric Placement – Last Deal Did Ok, but the Stock Has Done Very Well Since
- Applied Materials (AMAT US) (AM) is looking to raise approximately US$510m through an accelerated secondary offering for around 5% of Kokusai Electric (6525 JP)’s (KE) stock.
- KE had seen three selldown earlier, two from KKR and one from AM, with mixed results.
- In this note, we will talk about the placement and run the deal through our ECM framework.
6. Aequitas: Shin-Etsu Chemical Placement – A Relatively Small US$800m Deal
- A group of shareholders plan to raise around S$800m via selling some of their stake in Shin Etsu Chemical (4063 JP).
- This will be another large cross-shareholding unwind in Japan, although the shares haven’t done much recently.
- In this note, we talk about the deal dynamics and run the deal through our ECM framework.
7. Busy Ming Group (1768 HK) IPO – Thoughts on Valuation and the Outlook
- The IPO pricing of BUSY MING is attractive. P/E of 20-30x is an acceptable valuation range in the short term. The IPO pricing leaves certain upside potential for stock price.
- The profit situation of the franchisees is not optimistic. The rate of store closures is increasing. This makes us start to worry about the sustainability of BUSY MING’s franchise model.
- The current high growth may not be sustainable.BUSY MING clearly hopes to successfully IPO during the current peak period of performance, but investors may face performance decline in the future.
8. Aequitas: Shenzhen Han’s CNC Technology A/H Listing – Data Centre Beneficiary Offered At A Discount
- Shenzhen Han’s CNC Technology (301200 CH), a PCB production equipment solution provider, aims to raise around US$615m in its H-share listing.
- CNC Technology is a specialized Printed Circuit Board (PCB) production equipment solution provider in China, focused on the R&D and manufacturing of equipment used across key stages of PCB manufacturing.
- We have looked at the past performance and likely A/H premium in our previous note. In this note, we talk about the IPO pricing.
9. Aequitas: Muyuan Foods A/H Listing – Decent Pricing, Weak Momentum
- Muyuan Foodstuff Co Ltd A (002714 CH) , a leader in the hog farming industry, aims to raise around US$1.4bn in its H-share listing.
- MF is a leading pork company with over 30 years of expertise in the hog farming industry.
- We have looked at the past performance and likely A/H premium in our previous note. In this note, we talk about the IPO pricing.
10. Eastroc Beverage Hong Kong IPO Preview
- Eastroc Beverage Group (9980 HK) is getting ready to complete its IPO in Hong Kong next week. The company is selling 40.9 million shares for HK$248 each
- The company plans to raise up to HK$10.1 billion (US$1.3 billion). This would suggest a market cap of about US$21 billion.
- Eastroc Beverage is one of the largest functional beverage companies in China and the dominant domestic energy drink producer, with its Eastroc Special Drink product having displaced Red Bull product.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
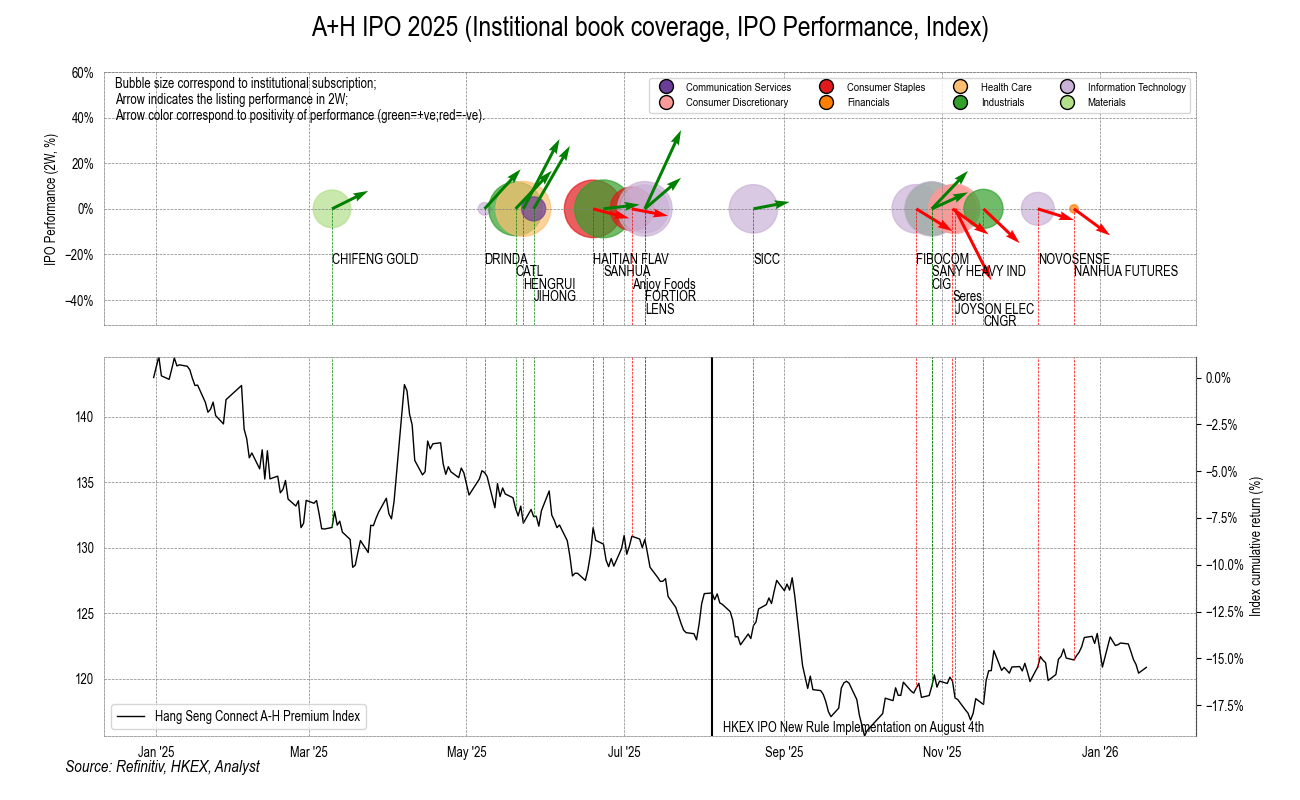
1. HK A+H IPO 2025: Essential Statistics Ahead of the 2026 Wave
- In this note, we take a statistical view of the A+H listing in 2025.
- We examine time-series trends in IPO performance, subscription dynamics, market sentiment, and sponsor performance.
- We also look at A-H premium dynamics post-listing and sector-level deal performance.
2. Busy Ming Hong Kong IPO Preview
- Busy Ming Group (1768 HK) is getting ready to complete its IPO in Hong Kong next week. The IPO price range is between HK$229.60 and HK$236.60.
- At the top of the range, it would bring in about HK$3.3 billion (US$420 million) and value the company at about HK$50.7 billion (US$6.5 billion).
- The company experienced explosive growth in the past four years, driven mainly by rapid store expansion and the Super Ming acquisition.
3. Aequitas: Sinotruk Placement – First Selldown Introduces Overhang After Strong Run-Up
- German truckmaker, MAN SE (via MAN Finance and Holding) is looking to sell a ~2% stake in Sinotruk Hong Kong (3808 HK) to raise upto US$207m via a secondary selldown.
- Sinotruk (Hong Kong) Ltd is China’s leading heavy-duty truck manufacturer, focused on commercial vehicles with strong domestic market share, growing exports, and consistent cash generation.
- In this note we talk about the deal dynamics and run the deal through our ECM framework.
4. Muyuan Foods A/H Listing – PHIP Updates and Thoughts on A/H Premium
- Muyuan Foodstuff Co Ltd A (002714 CH), a leader in the hog farming industry, aims to raise around US$1.5bn in its H-share listing.
- MF is a leading pork company with over 30 years of expertise in the hog farming industry.
- We have looked at the company’s past performance in our previous note. In this note, we talk about the recent updates and likely A/H premium.
5. Busy Ming (1768 HK) IPO: Not Expensive with Moderate Upside
- Busy Ming Group (1768 HK)‘s 3-year EPS CAGR of 43.1% places it ahead of most peers in F&B retailing, including the tea beverage sector.
- Operating on a franchise model, its 13x FY26F and 10.2x FY27F PERs are not expensive, as peers ex-Sun Art Retail (6808 HK) are averaging at 15x and 12.4x.
- It is difficult to trade at Mixue (2097 HK)‘s and Guming (1364 HK)‘s ~20x, due to lower margins. Our fair value is 16.5x PER, equalling HK$300.
6. Busy Ming (1768 HK) IPO: Uplifted Margins, Strong Volumes, Market Reach Make It A Compelling BUY
- Busy Ming (1768 HK) launched its Hongkong IPO aiming to raise up to HK$ 3.3B. The company plans to sell 14.1M shares at HK$229.6-$236.6 per share.
- Busy Ming Group is an established and growing food and beverage retailer in China. The company owns two popular brands, “Busy for You” and “Super Ming”.
- The growth outlook more than justifies the valuation. We would recommend the investors to subscribe to the issue and cash in on the secular growth story the company is offering.
7. Eastroc Beverage H Share Listing: The Investment Case
- Eastroc Beverage Group (605499 CH), the largest functional beverage company in China, is pre-marketing an H-Share listing to raise around US$1 billion.
- The product portfolio includes energy beverages, sports beverages, tea beverages, coffee beverages, plant-based protein beverages, fruit and vegetable juice beverages, and other beverage products.
- The investment case rests on a large TAM, a core business in good health, rising margins and strong cash conversion.
8. Busy Ming (1768 HK) IPO: Valuation Insights
- Busy Ming Group (1768 HK) is a food and beverage retailer in China. It has launched an HKEx IPO to raise up to US$428 million.
- I previously discussed the IPO in Busy Ming IPO: The Investment Case.
- In this note, I present my forecasts and valuation. My analysis suggests that the IPO price range is attractive.
9. Aequitas: Shadowfax IPO – Delivering a Decent Valuation Entry Point
- Shadowfax Technologies (1310315D IN) is looking to raise US$211m in its upcoming India IPO.
- Shadowfax Technologies is a third-party logistics (3PL) company that leverages a unified platform to facilitate digital commerce across India.
- We have looked at the company’s past performance in our previous note. In this note, we talk about valuations.
10. Aequitas: Busy Ming Pre-IPO- Priced at a Discount to Peers
- Busy Ming Group (BMG HK) is looking to raise up to US$430m in its upcoming Hong Kong IPO.
- It is a rapidly growing food and beverage retailer in China. Stores are typically located in high-traffic, high visibility, and easily accessible street-side locations.
- In this note, we examine the IPO dynamics, and look at the firm’s valuation.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
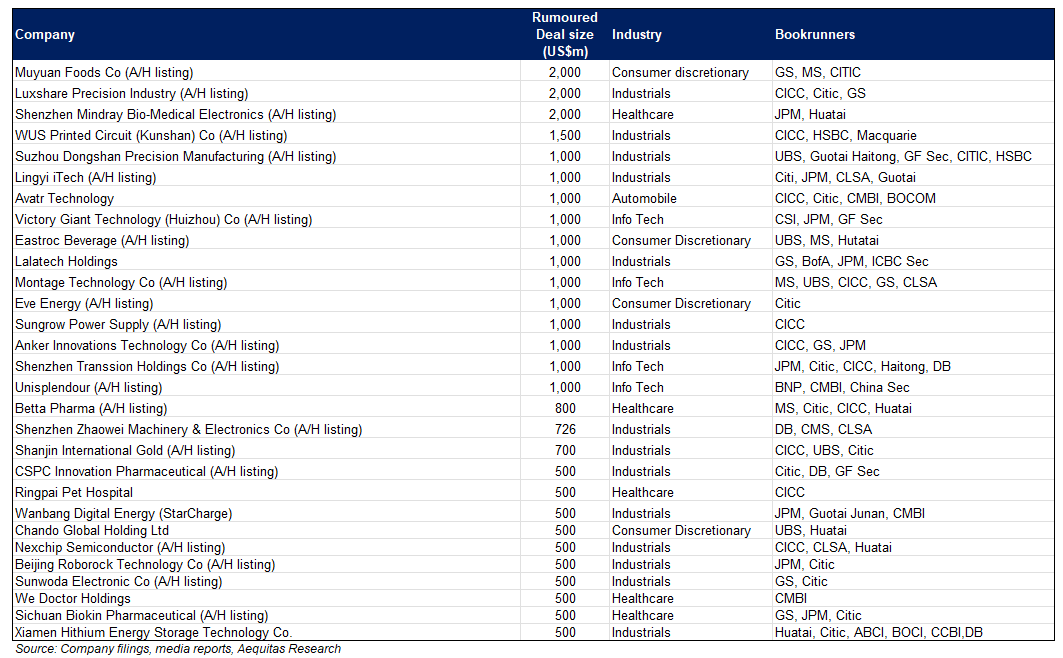
1. Aequitas 2026 Asia IPO Pipeline – Hong Kong
- In this note, we will take a look at the Asia Pacific IPO pipeline for 2026, starting with Hong Kong.
- This list has been compiled on a best effort basis from tracking the company filings and through various other sources.
- The deals you see in this note are only a part of our full IPO pipeline tracker. Feel free to drop us a message for additional information on these IPOs.
2. Wuxi Biologics Placement: Recent Deals Haven’t Done as Well
- WuXi Biologics Holdings is looking to raise US$460m from a partial selldown of its stake in Wuxi Biologics (2269 HK).
- WuXi Biologics Holdings had been continuously selling down its stake over the last few years.
- In this note, we will talk about the placement and run the deal through our ECM framework.
3. Initial Thoughts on the HD Hyundai Robotics IPO
- HD Hyundai Robotics is getting ready to complete its IPO in Korea in 2026. HD Hyundai Robotics is expected to be one of the largest IPOs in Korea this year.
- The market currently estimates the value of HD Hyundai Robotics to be about 6-7 trillion won, up from a recent private market valuation of 1.8 trillion won in October 2025.
- If HD Hyundai Robotics is valued at 7 trillion won, an 80% stake held by HD Hyundai would be worth 5.6 trillion won (31% of HD Hyundai’s market cap).
4. Montage Technology H Share Listing: The Investment Case
- Montage Technology (688008 CH), the world’s largest memory interconnect chip supplier, has filed its PHIP for an H Share listing to raise US$1 billion.
- In 2024, Montage was the largest supplier of memory interconnect chips, with 36.8% market share.
- The investment case rests on an industry-leading position, a robust core business, an improving margin profile, cash generation, and a reasonable valuation.
5. Pharmaron Beijing Placement: Shares Had a Good Start This Year
- Pharmaron Beijing (300759 CH) is looking to raise US$175m in its primary offering.
- The company plans to use the proceeds for project development, repayment of bank loans and as working capital.
- In this note, we will talk about the placement and run the deal through our ECM framework.
6. Sunway Healthcare Pre-IPO: Favorable Industry Positioning and Expansion Plan to Drive Growth
- Sunway Healthcare plans to offer up to 1,974M shares for its upcoming Malaysian IPO, comprising of up to 1,399M existing shares to be offered for sale and 575M new shares.
- Sunway intends to utilize IPO proceeds for greenfield and brownfield Capex and redemption of debt. The company aims to double its bed capacity by 2032.
- As one of the major hospital groups in Malaysia, Sunway is well-positioned to capitalize on industry’s growth opportunity and further solidify its presence in the private healthcare services industry.
7. IPO Rating: BitGo Holdings, Inc.
- BitGo IPO has launched and will trade on the New York Stock Exchange with a size of roughly 11.82 million shares priced with a range of $15 to $17 per share, targeting proceeds of around $189 million if priced at the mid-point.
- As a longstanding digital asset custody and infrastructure provider — serving thousands of institutional clients, managing tens of billions in assets, and operating one of the industry’s deepest custody platforms — BitGo sits at the intersection of crypto technology and institutional finance.
- The company has seen strong topline growth, with reported revenue surging as digital assets expanded in adoption, yet it also faces persistent margin pressure and industry cyclicality.
8. K Bank IPO Preview (Third Try Is a Charm?)
- K Bank is getting ready to complete its IPO on the KOSPI exchange in February 2026. This is the company’s third attempt at an IPO in the past several years.
- The IPO price range is from 8,300 won to 9,500 won, resulting in an offering value of approximately 498 billion to 570 billion won.
- The expected market caps range from 3.4 trillion won to 3.9 trillion won which are lower than the previous market cap range of 4.0 trillion won to 5.0 trillion won.
9. BitGo Files for NYSE IPO as Institutional Crypto Infrastructure Moves Into the Spotlight
- BitGo Holdings, Inc. has filed publicly for an initial public offering, positioning itself as one of the most established institutional crypto infrastructure providers to access the public markets in early 2026.
- The company plans to list its Class A common stock on the New York Stock Exchange under the ticker BTGO , offering 11.82 million shares at an expected price range of $15.00 to $17.00 per share .
- At the midpoint price of $16.00, the offering implies a gross deal size of approximately $189 million, excluding any overallotment.
10. Aequitas 2026 Asia IPO Pipeline – Japan & South Korea
- In this note, we will take a look at the Asia Pacific IPO pipeline for 2026, having looked at HK and India, we talk about Japan and South Korea pipeline.
- This list has been compiled on a best effort basis from tracking the company filings and through various other sources.
- The deals you see in this note are only a part of our full IPO pipeline tracker. Feel free to drop us a message for additional information on these IPOs.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. OmniVision H Share Listing (501 HK): Valuation Insights
- OmniVision Integrated Circuits Group (603501 CH), a CMOS image sensor (CIS) company, has launched an H Share listing to raise US$617 million.
- I discussed the H Share listing in OmniVision H Share Listing: The Investment Case.
- The proposed AH discount of 25.5% (based on the 30 December A Share price) is resonable, and I would participate in the H Share listing.
2. MiniMax IPO – Hype Will Help, Even as Government Regulations Starting
- MiniMax, a global AI foundation model company, aims to raise around US$540m in its Hong Kong listing.
- As of September 2025, its AI-native products had cumulatively served over 200m individual users across over 200 countries and regions.
- We have looked at the company’s past performance in our previous note. In this note, we talk about valuations.
3. MiniMax (100 HK) IPO: Valuation Insights
- MiniMax (MINIMAX HK), a global AI foundation-model company, is seeking to raise up to US$540 million. Pricing is on 7 January.
- I discussed the H Share listing in MiniMax (100 HK) IPO: The Investment Case.
- The IPO price range is attractive compared to the last reported valuation rounds and revenue targets of its three private pure-play competitors.
4. Kanzhun Placement – Decent Performance but Liquidity Plays a Factor
- Tencent Holdings (via Image Frame Investment) aims to raise around US$205m via selling a part of its stake in Kanzhun (2076 HK).
- Kanzhun is a Nasdaq and Hong Kong-listed Chinese job listing portal. Kanzhun runs BOSS Zhipin APP, which allows enterprise users and jobseekers to directly chat, providing more convenience to both.
- In this note we talk about the deal dynamics and run the deal through our ECM framework.
5. Montage Technology A/H Listing – PHIP Updates and Thoughts on A/H Premium
- Montage Technology (688008 CH) (MT), a provider of memory interface chips and interconnect chips, aims to raise around US$1bn in its H-share listing.
- MT’s product portfolio, mainly comprises memory interface chips and interconnect chips, addresses interconnect bottlenecks while enhancing data rate/bandwidth, reliability, and power efficiency, as per the company.
- We have looked at the company’s past performance in our previous note. In this note, we talk about the recent updates and likely A/H premium.
6. Pre-IPO MiniMax Group – About the Business Model, the Concerns and Thoughts on Valuation
- MiniMax’s “multimodal + heavy product” approach does show strong revenue growth potential, but cost pressure of this “multimodal operation” is clear. The profitability of MiniMax’s core C-end business is weak.
- The high-end pricing of its IPO reflects more the market’s optimism about China’s AI global narrative and short-term growth momentum rather than a valuation based on a robust financial model.
- Considering Zhipu AI’s higher gross margin based on its B-end technology path, we think in the short term, reasonable MiniMax’s valuation is close to or slightly lower than Zhipu AI.
7. OmniVision Integrated Circuits Group A/H Listing – Needs More Discount
- OmniVision Integrated Circuits Group (603501 CH), a semiconductor company, aims to raise around US$600m in its H-share listing.
- OVIC, is the world’s third largest smartphone CIS and the largest automotive CIS provider with a market share of 32.9% based on revenue in 2024, according to Frost & Sullivan
- We have looked at the past performance and likely A/H premium in our previous note. In this note, we talk about the IPO pricing.
8. Aequitas 2025 IPOs and Placements Performance Review – HK Breached COVID Peak, India Flow Strong
- 2025 marked our tenth year covering Equity Capital Markets (ECM) in Asia Pacific. In 2025, IPO volumes were driven by a strong rebound in HK, while India flow remained resilient.
- We ended 2025 with an accuracy rate of 72.2% across 119 IPOs that we covered and 64.3% across 125 placements.
- For those not familiar with our coverage, we aim to cover all IPOs and placements with a minimum deal size of US$100m across Asia-Pacific, including China ADRs.
9. MiniMax Group (100 HK) IPO: Estimate of Fair Value
- MiniMax (100 HK) is a viable AI foundation model company, with highly ranked product suites and increasingly more adoption by customers around the world.
- The fair value is at HK$216 per share, reflecting its strong potential to capture the AI growth, solid market position and the scarcity value on the Hong Kong market.
- At fair FY27F P/S of 48.8x, this equals 18% discount to the Moore Threads Intelligent (688795 CH) and 35% premium to Shanghai Biren Technology (6082 HK).
10. Aequitas: MiniMax IPO Trading – Highest AI Linked Coverage so Far
- MiniMax Group (100 HK), a global AI foundation model company, raised around US$700m in its Hong Kong listing.
- As of September 2025, its AI-native products had cumulatively served over 200m individual users across over 200 countries and regions.
- We have looked at the company’s past performance and valuations in our previous note. In this note, we talk about the trading dynamics.