
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
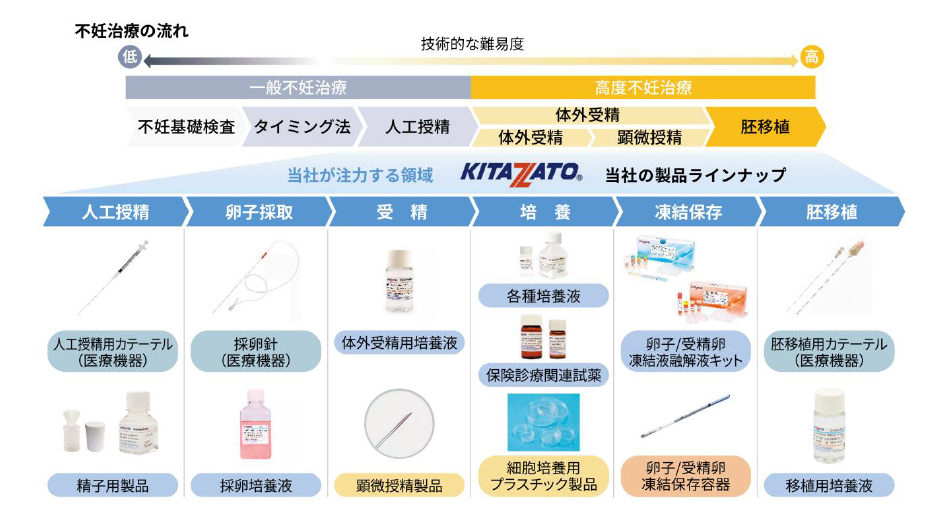
1. Kitazato Pre-IPO – Past Sales Have Been Steady but Slowing
- Kitazato (368A JP) manufactures and sells medical devices and products for fertility treatment. It aims to raise around US$120m in its Japan IPO.
- Kitazato specializes in artificial insemination, in vitro fertilization, cell cryopreservation and reproductive engineering technologies in regenerative medicine.
- In this note, we look at its past performance and other deal dynamics that might impact the listing.
2. Virgin Australia IPO – Not Terribly Exciting, After Significant Items Adjustment
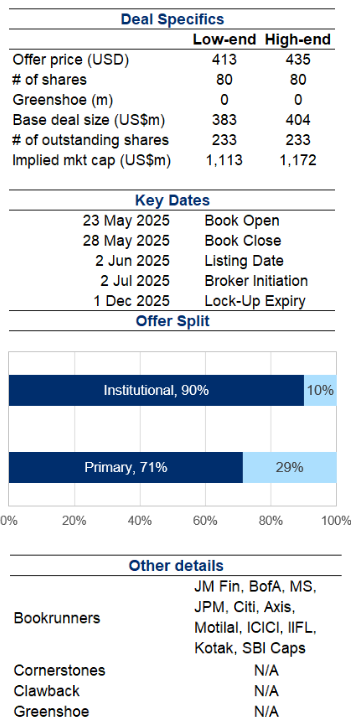
- Bain Capital is looking to raise around US$440m via selling some of its stake in Virgin Australia Holdings (VAH AU).
- Virgin Australia is the second largest airline group operating in the Australian aviation market, with an average 32% domestic RPT capacity market share in CY24.
- In this note, we look at the company’s past performance and provide our thoughts on valuations.
3. Kelun-Biotech Placement – Recent Run-Up Makes Its Tricky
- Sichuan Kelun-Biotech Biopharm (6990 HK) is looking to raise up to US$200m from a primary placement. The offering is priced at HK$ 330.2-341, a 5-8% discount to last close.
- The company plans to use the proceeds for research and development, clinical trials of its core products and as working capital.
- In this note, we will talk about the placement and run the deal through our ECM framework.
4. Wistron GDR Offering – Well Flagged US$922m Offering, Discount Slightly Wider than Recent Deals
- Wistron Corp (3231 TT) is looking to raise up to US$922m in its global depository receipts (GDRs) offering.
- Similar to previous GDR listings, the firm has undergone a long drawn out process prior to launching the deal, having to jump through a number of board/shareholder/regulatory approval loops.
- In this note, we run the deal through our ECM framework and comment on deal dynamics.
5. Primo Global Pre-IPO: Driven by Domestic Demand as International Ops Falter
- Primo Global (367A JP) is looking to raise at least US$104m in its upcoming Japan IPO.
- Primo Global specializes in merchandising bridal jewellery, namely engagement rings and wedding rings.
- In this note, we look at the firm’s past performance.
6. Circle IPO Analysis (Second Largest Issuer of Stablecoins Globally)
- Circle raised both the IPO shares to be issued and IPO price range. New IPO price range is $27 to $28 per share (from $24 to $26 per share previously).
- We have a Positive View of the Circle due to its status as the second largest issuer of stablecoins globally, rapidly increasing user base and sales, and improving profit margins.
- Major risk factors of this IPO include CBDCs, centralization, cyberattacks, and potential government crackdown.
7. ECM Weekly (2 June 2025) -Indigo, ITC, EBOS, Isuzu, Foshan Haitian, Lens Tech, Seres, Schloss, Aegis
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, Foshan Haitian Flavouring & Food (603288 CH) might launch its A/H listing this week.
- On the placements front, there were a number of large deals across the region, with notable ones in ITC Ltd (ITC IN) and InterGlobe Aviation Ltd (INDIGO IN).
8. Aegis Vopak IPO: Anemic Demand
- Aegis Vopak Terminals Ltd (1902844D IN) raised about US$328m in its upcoming India IPO.
- It is the largest Indian third-party owner and operator (in terms of storage capacity) of tank storage terminals for liquified petroleum gas (LPG) and liquid products.
- In our previous notes, we talked about the company’s historical performance, undertook a peer comparison and shared our thoughts on valuation. In this note, we talk about the trading dynamics.
9. Pre IPO Eastroc Beverage Group (H Share) – The Strength, the Concerns and the Outlook
- 2024 is a milestone year. The weighted average ROE set a new high. Due to cost dilution brought by economies of scale, net profit growth was higher than revenue growth.
- The risk of relying on a single category hasn’t been eliminated. Traditional advantages of offline channels are becoming saturated. There is a gap between channel structure and new consumer forces
- Eastroc’s valuation is expected to be higher than the industry average and peers due to its higher growth rate, but investors needs to consider the H/A premium
10. Slide Holdings Insurance, Inc.(SLDE): Peeking at the IPO Prospectus of Another Florida Based Insurer
- They write several homeowners’, condominium owners’, and commercial residential products in coastal specialty markets in Florida and South Carolina.
- For the three months ended March 31, 2024 and March 31, 2025, they had gross premiums written of $245 million and $278 million.
- The strong performance of peers could provide a potential tailwind for this IPO.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Schloss Bangalore IPO – Thoughts on Peer Comp and Valuation
- Schloss Bangalore Ltd (SCHBL IN) is looking to raise about US$409m in its India IPO. The deal has been downsized from an earlier size of around US$600m.
- It is a luxury hospitality company which owns, operates, manages and develops luxury hotels and resorts under ‘The Leela’ brand, through direct ownership and hotel management agreements with third-party owners.
- In this note, we will talk about the IPO valuations.
2. Curator’s Cut: Korea’s Value, CATL’s Charge and Copper’s Surge
- Welcome to Curator’s Cut, a fortnightly roundup of standout themes from the 1,200+ insights published over the past two weeks on Smartkarma
- In this cut, we look at Korea’s compelling valuation versus AxJ equities, CATL’s blockbuster Hong Kong listing and its market implications, and explore copper’s price surge amidst Chinese demand
- Want to dig deeper? Comment or message with the themes you think should be highlighted next
3. [Japan ECM] Financial Crossholders Offering Isuzu (7202) – Big Buyback Covers Most Of The Back End
- In line with the trend of financial institutions led by non-life insurers selling out of their cross-holdings, today we get an offering of shares held in Isuzu Motors (7202 JP).
- Today we got an announcement of 29.28mm shares being offered by a dozen financial institutions and a greenshoe for 15% more. At a 10% discount from here it’s ¥57bn/US$400mm.
- It is 16 days of ADV, which is big, but the company also announced a ¥50bn buyback from Pricing+6 to end of March 2026. That should stabilise things.
4. HK Strategy: Some Consumer IPO Pipelines and Their Proxies
- Hong Kong’s IPO market has gathered momentum lately, especially with the overwhelming response to CATL (3750 HK). Consumer IPOs are the next ones to gather interest.
- Foshan Haitian Flavouring & Food Co (FHF HK) is the most imminent one, potentially seeking up to US$1bn. Without significant peers in Hong Kong, it should attract good attention.
- The other interesting ones include Zhou Liu Fu Jewellery Co., Ltd. (1716396D CH), Three Squirrels (TRS HK), and Eastroc Beverage Group (EBG HK).
5. Interglobe Aviation (Indigo) Placement – Another US$800m+ Deal by Co-Founder
- InterGlobe Aviation Ltd (INDIGO IN)‘s co-founder, Rakesh Gangwal, aims to raise around US$803m via selling around a 3.3% stake in Indigo.
- He had earlier stated his intention to pare down his stake after a long drawn, and very public battle, with his co-founder Rahul Bhatia. He has sold many times before.
- In this note, we run the deal through our ECM framework and comment on deal dynamics.
6. Foshan Haitian Flavouring H Share Listing: The Investment Case
- Foshan Haitian Flavouring & Food (603288 CH), a leading Chinese pharmaceutical company, has filed its PHIP for an H Share listing to raise US$1 billion.
- Foshan Haitian Flavouring & Food Company (FHF HK) has been China’s leading condiments company in terms of sales volume for 28 consecutive years.
- The investment case rests on its market positioning, return to growth, industry-leading profitability, cash generation and strong balance sheet. However, the valuation of the A Shares is full.
7. Isuzu Motors Placement – Relatively Small Deal Along with Buyback
- A group of shareholders aims to raise around US$380m via selling around 4% of Isuzu Motors (7202 JP).
- Being another cross-shareholding unwind in Japan, it shouldn’t carry much negative connotations, in our view.
- In this note, we will talk about the placement and run the deal through our ECM framework.
8. Foshan Haitian Flavouring A/H Listing – PHIP Updates and Thoughts on A/H Premium
- Foshan Haitian Flavouring & Food (603288 CH) (FHCC), China’s leading condiments company, now aims to raise around US$1bn in its H-share listing.
- FHCC is China’s leading condiments company within its main product categories of soy sauce, oyster sauce, flavored sauce, specialty condiment products and other products.
- We have looked at the past performance in our earlier note. In this note we talk about the PHIP updates and likely A/H premium.
9. ECM Weekly (26 May 2025) – CATL, Hengrui, Eastroc, Haitian, Schloss, Aegis, Hyundai Marine, Pony
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, Contemporary Amperex Technology (CATL) (300750 CH) and Jiangsu Hengrui Pharmaceuticals (1276 HK) performance has paved the way for a slew of A/H listings to follow.
- On the placements front, there was a large selldown in HD Hyundai Marine Solution (443060 KS) and a lockup release for Pony AI (PONY US) is coming up.
10. Capitaland Ascendas REIT Placement: DPU and NAV Accretive
- CapitaLand Ascendas REIT (CLAR SP) is looking to raise at least S$500M in a private placement, to fund the acquisition of some valuable properties.
- These acquisitions will expand the firm’s portfolio exposure to Singapore and data centers.
- In this note, we comment on the deal dynamics and run the deal through our ECM framework.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. GMO Internet (4784) – Squeeze-Able So Squeezing, Offering Likely Gets Pulled – AVOID LIKE THE PLAGUE
- GMO Internet (4784 JP) was created by the reverse takeover of a listed cad/media company by its parent company’s “internet infrastructure” business. GMO Internet Group ended up with ~98%.
- In the process, the stock rose 500%. Now, as part of its promise to the TSE allowing TSE Prime membership for the extraordinarily low-float target, the parent is offering shares.
- The squeeze has it at 180x Dec25e EPS, 111x EBIT, 70x book. The offering likely gets pulled and the stock isn’t shortable… so what next? Pain, and an ECLWO.
2. CATL A/H Trading – Strong Demand, Upsized, Included in Short-Sell List
- Contemporary Amperex Technology (CATL) (300750 CH), one of the world’s largest battery solutions providers, raised around US$5.2bn in its H-share listing.
- Contemporary Amperex Technology (3750 HK) is the global leader in new energy vehicle battery solutions, in China and globally, as per SNE Research. Its A-shares have been listed since 2018.
- We have looked at the company’s past performance and valuations in our earlier notes. In this note, we talk about the trading dynamics.
3. GMO Internet Placement: Extremely Overvalued at the Moment
- GMO Internet Group (9449 JP) is looking to sell its 33.4% stake in its subsidiary GMO Internet (4784 JP) to meet free-float requirements.
- Shares are very overvalued at the moment and should be worth a mere fraction of its current trading value.
- We have looked at the company’s deal dynamics in our earlier notes. In this note, we discuss the firm’s outlook as well as valuation.
4. Jiangsu Hengrui Pharma H Share Listing (1276 HK): Trading Debut
- Jiangsu Hengrui Pharmaceuticals (1276 HK) priced its H Share at HK$44.05 to raise HK$9,890.1 million (US$1.3 billion) in gross proceeds. The H Share will be listed tomorrow.
- The timing of the H Share listing is fortuitous, as the peers have materially re-rated since the prospectus was released on 15 May.
- Hengrui had the highest oversubscription rates among recent large AH listings. The AH discount implied by the offer is attractive.
5. CATL H Share Listing (3750 HK) IPO: Trading Debut
- Contemporary Amperex Technology (3750 HK) priced its H Share at HK$263 to raise HK$35,657.2 million (US$4.6 billion) in gross proceeds. The H Share will be listed tomorrow.
- The H Share listing price implies an AH discount of 6.6% at the A Share price of RMB63.51. This compares to Midea Group (300 HK)‘s AH discount of 4.7%.
- CATL had the highest oversubscription rates among recent large AH listings. Our valuation analysis suggests that the H Share listing price is attractive.
6. Eastroc Beverage A/H Listing – Energized – Fast Growth, Better Margins
- Eastroc Beverage Group (605499 CH) (EB), a China-based functional beverage company, aims to raise around US$1bn in its H-share listing.
- According to Frost & Sullivan (F&S), EB has been the largest functional beverage company in China in terms of sales volume for four consecutive years since 2021.
- In this note, we look at its past performance and other deal dynamics that might impact the listing.
7. ECM Weekly (19 May 2025) – CATL, Hengrui, Green Tea, SMPP, Unisound, Renesas, Genda, GMO, PayTM
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, Contemporary Amperex Technology (CATL) (300750 CH) and Jiangsu Hengrui Medicine (600276 CH) will remain in the spotlight in the coming week as well.
- On the placements front, Japan deals appear to be picking up again.
8. HD Hyundai Marine Placement – Very Well Flagged, Overhang Easing but Last Deal Didn’t Do Well
- KKR is looking to raise around US$410m via selling some of its stake in HD Hyundai Marine Solution (443060 KS).
- KKR had come out of its IPO linked lockup in Nov 2024 and had tried to launch a deal in Dec 2024 and finally undertook a deal in Feb 2025.
- In this note, we will talk about the placement and run the deal through our ECM framework
9. Hanwha Aerospace: Higher Rights Offering Price and Amount
- On 21 May, Hanwha Aerospace (012450 KS) announced that the rights offering price increased to 684,000 won (up 26.9% from 539,000 won previously) due to recent increase in price.
- Due to the higher rights offering price, the scale of the capital raise has increased from 2.3 trillion won previously to 2.9 trillion won (US$2.1 billion).
- Issue price is determined by applying a 15% discount rate to the one-month weighted arithmetic average price, one-week weighted arithmetic average price, and the closing price on the base date.
10. PegBio 派格生物 IPO: A Hardsell but Mostly Done Deal
- PegBio, a China-based near commercial stage biotech company, launched its IPO to raise up to US$39m via a Hong Kong listing.
- We have previously covered the company’s fundamentals and valuation. We highlight issues of the company.
- In this note, we look at the deal term. We think the valuation is demanding, but the company managed to get support from local government facilitate its listing.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. POSCO Future M: A Rights Offering Capital Raise of 1.1 Trillion Won
- Posco Future M (003670 KS) announced today that it plans to complete a rights offering capital raise of 1.1 trillion won.
- The capital raise will involve 11.483 million new shares, representing 14.8% of current outstanding shares. The expected rights offering price is 95,800 won, which is 15.8% lower than current price.
- We have a Negative view on POSCO Future M and this capital raise, which is likely to have a negative impact on its shares due to the dilution risk.
2. GMO Internet (4784) Offering – This Is a GINORMOUS Re-IPO – AVOID LIKE THE PLAGUE
- Last year, GMO injected its internet business into GMO Internet (4784 JP) and took shares as consideration. Somehow, GMO Internet got a TOPIX inclusion earlier this year.
- The company has 1.24% float of 3.4mm shares. GMO Internet Group – the parent – will now offload 91.7mm shares in an equity offering to meet TSE Continued Listing Requirements.
- That is about ¥279bn at current price against float of ¥10bn. Full market cap is ¥850bn. That’s 170x Dec25e Net Income. I expect the price will fall. You were warned.
3. CATL H Share Listing (3750 HK): Valuation Insights
- Contemporary Amperex Technology (CATL) (300750 CH) has launched its H Share listing at a maximum price of HK$263. Pricing will be on 19 May, and the listing on 20 May.
- I discussed the H Share listing in CATL H Share Listing: The Investment Case, CATL H Share Listing: AH Discount Views, CATL H Share Listing: PHIP Reinforces the Investment Case.
- Our valuation analysis suggests that the low AH discount can be justified. We would participate in the listing.
4. CATL A/H Listing – High Quality, Large Size Make It Unavoidable but Needs a Discount
- Contemporary Amperex Technology (CATL) (300750 CH) , one of the world’s largest battery solutions providers, aims to raise around US$4bn in its H-share listing.
- CATL is the global leader in new energy vehicle battery solutions, in China and globally, as per SNE Research. Its A-shares have been listed since 2018.
- We have looked at the company’s past performance in our earlier notes. In this note, we talk about the IPO pricing.
5. GENDA Placement – Good Track Record & Sort off Well Flagged but Relatively Large
- GENDA (9166 JP), along with a selling shareholder, is looking to raise around US$190m to partly fund its M&A.
- Genda develops and operates amusement facilities in Japan, primarily operating under its Genda GiGO Entertainment subsidiary.
- In this note, we will talk about the placement and run the deal through our ECM framework.
6. CATL A/H Listing – More like ADR Secondary Listing than an A/H Listing – Performance & Subscription
- Contemporary Amperex Technology (CATL) (300750 CH) , one of the world’s largest battery solutions providers, aims to raise around US$4bn in its H-share listing.
- CATL is the global leader in new energy vehicle battery solutions, in China and globally, as per SNE Research. Its A-shares have been listed since 2018.
- In this note, we talk about the IPO pricing and how it compares to some of the past listings.
7. Curator’s Cut: “Bubble” Tea, Japan M&A 🍿and TSMC from Different Lenses
- Welcome to Curator’s Cut, a fortnightly roundup of standout themes from the 1,200+ insights published over the past two weeks on Smartkarma
- In this cut, we look through the bubble in Chinese tea company listings, the recent entertainment provided by Japanese M&A situations and the varied ways analysts look at TSMC on Smartkarma
- Want to dig deeper? Comment or message with the themes you think should be highlighted next time
8. GMO Internet Placement: Secondary Sell-Down (Quasi IPO) To Meet Prime Listing Requirements
- GMO Internet Group (9449 JP) is looking to sell its 33.4% stake in its subsidiary GMO Internet (4784 JP) to meet free-float requirements.
- As the current free-float is tiny, the deal is more like a quasi-IPO rather than a placement, in our view.
- In this note, we will talk about the deal dynamics as well as updates on the company’s financial performance.
9. GMO Internet (4784 JP): A Huge US$1.9 Billion Secondary Offering
- GMO Internet (4784 JP) has announced a secondary offering of 91.7 million shares, worth around US$1.9 billion.
- The selling shareholder is GMO Internet Group (9449 JP). The secondary offering aims to increase the tradable share ratio to satisfy the TSE Prime Market’s continued listing criteria.
- The offering represents 239.4 days of the 1-year ADV, the highest compared to the recent large Japanese placements. Pricing is likely to be on 5 June.
10. Jiangsu Hengrui Pharma A/H Listing – Low-End Is Probably Close to Fair Value
- Jiangsu Hengrui Medicine (600276 CH), a China-based pharmaceutical company, aims to raise around US$1.3bn in its H-share listing.
- JHP Has been ranked as one of the global Top 50 pharmaceutical companies by Pharm Exec for six consecutive years since 2019.
- We have looked at the company’s past performance and other deal dynamics in our previous note. In this note, we talk about the IPO pricing.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. CATL: Launch of Book Building for Hong Kong Listing
- According to Reuters, CATL plans to launch its Hong Kong listing process including book building during the week of 12 May.
- We estimate CATL to generate revenue of 423.6 billion RMB (up 17% YoY) and net profit of 55.6 billion RMB (up 13.1% YoY) in 2025.
- Our base case valuation of CATL is implied market cap of 1.3 trillion CNY which is 32% higher than current market cap. We believe CATL’s shares are undervalued.
2. CATL H Share Listing: PHIP Reinforces the Investment Case
- Contemporary Amperex Technology (CATL) (300750 CH), the world’s largest supplier of EV and ESS batteries, has filed its PHIP for an H-Share listing to raise US$5 billion.
- I previously discussed the H Share listing in CATL H Share Listing: The Investment Case and CATL H Share Listing: AH Discount Views.
- In this note, I examine the latest results and developments outlined in the PHIP. Overall, the PHIP reinforces my positive view.
3. Laopu Gold (6181 HK): Heritage Luxury, Guochao Appeal. Key Facts, Financials & Valuation
- Laopu Gold (6181 HK) targets to raise approximately USD350 mn from a primary placement of 4.31 million new shares at HKD630 per share.
- Laopu Gold has delivered both superior margins and rapid growth by marrying cultural resonance, premium pricing, artisanal excellence, and outstanding store economics.
- Laopu’s growth track record coincides with period of rising gold prices. Investors should weigh its impressive margins and brand strength against the risk of a less supportive gold price environment.
4. EToro Group Ltd (ETOR): Retail Trading Platform Eyeing $4b Valuation; BlackRock in on the IPO
- The company set terms with a F-1/A putting 10 million shares for sale at a range of $46-$50 which would value the company as high as $4.05b.
- BlackRock and funds managed by BlackRock placed a 20-percent cornerstone investment order and is on the cover of the prospectus.
- The blueprint to getting an IPO out the door during this time is to shrink the size of the transaction, bring in a cornerstone investor and provide an attractive valuation.
5. CATL A/H Listing – PHIP Updates and Updated Thoughts on A/H Premium
- Contemporary Amperex Technology (CATL) (300750 CH), one of the world’s largest battery solutions providers, aims to raise around US$5bn in its H-share listing.
- CATL is the global leader in new energy vehicle battery solutions, in China and globally, as per SNE Research. Its A-shares have been listed since 2018.
- We have looked at the company’s past performance and valuations in our earlier notes. In this note, we talk about its recent updates and provide updated thoughts on valuations.
6. ECM Weekly (5 May 2025) – CATL, Chery, Ather, Drinda, Eco-Shop, Green Tea, DN Sol, Lotte Glo, Hanwha
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, Contemporary Amperex Technology (CATL) (300750 CH) is said to be gearing up for an IPO launch this month, as per media reports.
- On the placements front, Hanwha Ocean (042660 KS) was the only sizable placement over the past week that we covered.
7. EToro IPO Valuation: First-Day IPO Pop Is Possible, But The Stock May Struggle To Hold Gains
- EToro Group Ltd., a social trading platform, sets terms for upcoming IPO in the United States. The online broker offers 10M Class A shares at range of $46.00-$50.00 per share.
- At the midpoint of price range, eToro would command a market value of ~$4B on a fully-diluted basis. The selling shareholders offer 5M Class A shares.
- BlackRock has indicated a non-binding interest in purchasing up to $100M worth of eToro shares. However, these shares will not be subject to a lock-up agreement.
8. Ant Group Considering on Listing Overseas Unit Ant International in Hong Kong
- Ant Group is considering on listing its overseas unit Ant International in Hong Kong. Ant International contributes approximately 20% to Ant Group’s total revenue.
- Ant International operates four core business lines: Alipay+ (cross-border payment platform), Antom (global merchant acquiring network), WorldFirst (remittance service), and Bettr (digital payment solution).
- Given the growing political to delist Chinese stocks from the US exchanges, there could be a greater political pressure on the Chinese government to approve Chinese IPOs in Hong Kong.
9. Green Tea Group IPO – Peer Comp & Thoughts on Valuation
- Green Tea Group (GTG) is looking to raise US$157m (HKD 1.2bn) in its upcoming Hong Kong IPO.
- GTG is the fourth largest Casual Chinese Cuisine player in Mainland China, it has been gaining market share historically and is likely to continue.
- GTG plans to accelerate its expansion of the restaurant network, focusing on expansion into tier two cities and below, with small restaurants rather than large ones.
10. Jiangsu Hengrui Pharma H Share Listing: The Investment Case
- Jiangsu Hengrui Medicine (600276 CH), a leading Chinese pharmaceutical company, has filed its PHIP for an H Share listing to raise US$2 billion.
- Jiangsu Hengrui Pharmaceuticals (JHR HK) ranked first among Chinese pharma companies in revenue from NME drugs in 2023 and the number of commercialised NME drugs in 2024.
- The investment case rests on its product portfolio, strong revenue growth, rising profitability, cash generation, strong balance sheet and undemanding valuation.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Samsung SDI Rights Trade Period & Short Ban: Quick Clarity
- Samsung SDI kept the trading window open until May 12, not May 9 — so stock rights will trade for a total of six sessions.
- If all shorts are closed by May 16, we can still subscribe. Spot hedging isn’t allowed, but outright shorts for pricing plays are fine.
- Entry cost is effectively capped at 146,200 won, and it’s still very unlikely the final price exceeds that, so using it as the rights entry cap still makes sense.
2. Hanwha Ocean Placement – Recent Run-Up, Results Make It Tricky
- Korea Development Bank (KDB) plans to raise around US$740m via selling around 5%+ stake in Hanwha Ocean (042660 KS).
- HO’s shares have nearly tripled since the start of the year, and the company reported its results today.
- In this note, we will run the deal through our ECM framework and talk about the recent updates.
3. KDB’s Hanwha Ocean Block Deal: Worth Taking a Swing
- KDB sells 4.3% of total shares, offloading about one fifth of its holdings. The price range was 81,265–81,710 won, at an 8.51–9.00% discount, totaling 1.056–1.062 trillion won.
- With more float and passive buying (KOSPI 200) potential, plus shipbuilding momentum, the stock’s pullback likely won’t exceed today’s discount — it might be worth taking a swing.
- There’s buzz KDB might sell its HMM stake through block trades, like Hanwha Ocean. However, with HMM’s cash reserves, a tender offer seems more likely to drive stock action instead.
4. Hainan Drinda New Energy (A/H IPO) – Business Was Acquired for 1/3rd the Price, Three Years Ago
- Hainan Drinda Automotive Trim (002865 CH) plans to raise up to US$234m via its A/H listing.
- HDNET is a specialized manufacturer of PV cells which are used in making PV modules.
- In this note, we look at the company’s recent performance and other deal dynamics, as well as valuations.
5. Hanwha Aero Capital Raise: Latest Timeline, Pricing Details, and Key Trading Factors
- The first pricing is May 20, ex-rights on May 22, and rights trading runs June 16-20. Final pricing is June 26, with subscription July 1, and shares trade July 21.
- The FSS is unlikely to make this a political issue, especially with Hanwha’s detailed amended filing. The rights offering should go ahead, so we’re prepping for that in trading.
- It’s similar to SDI, focusing on stock rights to lower entry cost. The offering size dropped 30%, but defense sector volatility and intense short action could still cause price swings.
6. Pre-IPO Green Tea Group (PHIP Updates) – Some Points Worth the Attention
- The decline in Green Tea’s performance in 2024 cannot be solely attributed to external factors such as economic downturn and the decline in consumption. There are deeper reasons behind it.
- The growth is mainly contributed by delivery service. However, commission fee is high and average spending per order is lower than dine-in services.So delivery service has limited contribution to profits.
- The aggressive expansion of restaurants may further dilute the performance of individual restaurant. We shared our three-year forecast.Valuation of Green Tea could be lower than Xiaocaiyuan and the industry average
7. DN Solutions IPO Officially Withdrawn: Background and Key Takeaways
- Book built weak, even under ₩65,000. Both local and foreign demand was super soft. Company floated printing at the bottom, but floor didn’t hold. Now, the deal is officially dead.
- The real overhang was valuation; the IPO priced too high for the growth story. Without a strong momentum trade, DN Solutions couldn’t ride the wave, and sentiment soured fast.
- They’re not waiting too long — likely aiming for a H2 comeback. KRX might skip the full review, and they may focus on domestic investors this time without an OC.
8. ECM Weekly (28 Apr 2025) – Ather, DN Solutions, Lotte, BenQ, Dorf-Ketal, Hi-Think, Kakao, Waaree
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, Ather Energy, DN Solutions (298440 KS) and Lotte Global Logistics were live this week, with few other gearing up for launches in Hong Kong.
- On the placements front, Kakao Corp (035720 KS) was the only sizable placement over the past week. We did look at a few more IPO linked lockup expiries.
9. Kayou IPO Preview: 250%+ Growth + FCF of $500M+ in 2024, Leader in the Trading Card Sector in China
- Kayou Inc., early-mover in the trading card industry in China, filed for an IPO in Hong Kong. The company sells trading cards, toys, figures, badges, pens, and notebooks, among others.
- Kayou Inc. received capital of ~$135M from HongShan Capital and Tencent Holdings in 2022. Mr. Li Qibin founded trading card and collectible toy firm in 2011.
- Founder led company has delivered 250%+ growth and FCF of $500M+ in 2024. The market opportunity is large enough to support sustained high growth for Kayou for several years.
10. Hanwha Aerospace Rights Offering – Third Time Is a Charm?
- Hanwha Aerospace (012450 KS) has once again provided a revised rights offering prospectus following another request from the Financial Supervisory Service (FSS).
- Rights offering amount remains the same at 2.3 trillion won. Expected rights offering price is 539,000 won which is subject to change. New shares listing date is 21 July 2025.
- Hanwha Aerospace reported sales of 5.5 trillion won (14.3% better than consensus) and operating profit of 560.8 billion won (11.7% better than consensus) in 1Q 2025.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. GMO Internet (4784) DropDown Holdco Gone Ballistic – Squeezed on Truly Tiny Float
- Gmo Ad Partners (4784 JP) has become GMO Internet as of 1 January 2025. On that day, it merged with the “internet infrastructure business” of GMO Internet (9449 JP).
- It was a kind of reverse takeover – a backdoor listing – and it on 24-Dec-2024, it was announced GMO Internet would move from TSE Standard to TSE Prime end-Jan2025.
- The stock is +300% since then. Why? A squeeze. Share count increase? 15x. Float share increase? Zero. Resulting Real World Float? 1.24% of shares out and about to shrink.
2. Trading LG Chem’s Large-Scale EB Issuance Backed by LG Energy Shares
- With a $2B deal expected, LG Chem will likely issue before end June as the 2023 EB’s put date nears and redemption pressure builds amid strained financials.
- Two years ago, hedge shorting spiked post-issuance and post-exchange start, but price impact was mild—only 3% and 6% drops—likely due to strong sector sentiment then.
- Sector sentiment’s turned sharply, so more aggressive price action is likely post-EB announcement. Timing is tricky, but the setup’s worth watching closely.
3. DN Solutions IPO – Tariffs, Peer Correction Don’t Help
- DN Solutions (298440 KS) (DNS) aims to raise around US$1.1bn in its Korea IPO via selling a mix of primary and secondary shares.
- DNS is engaged in the manufacture and sale of machine tools and the business of automation solutions and services related thereto.
- In our previous note, we looked at the company’s past performance and valuations. In this note, we talk about the updates since then.
4. Kakao Corp Placement – Momentum Isn’t Great but It Is a Small Deal
- SK Telecom (017670 KS) plans to raise around US$280m via selling its 2%+ stake in Kakao Corp (035720 KS).
- Kakao’s recent performance hasn’t been particularly great and the stock has been suffering even since the Kakao Pay management scandal in 2021.
- In this note, we will run the deal through our ECM framework and talk about the recent updates.
5. Initial Thoughts on the Sono International IPO
- Sono International, the largest resort operator in Korea, is getting ready to complete its IPO in 3Q 2025.
- Company is aiming for valuation of about 3 trillion won. Treasury shares accounted for 35.93% of total outstanding shares at the end of 2024.
- One of the noticeable aspects of the company’s income statement is that although the company’s sales growth was modest from 2019 to 2024, its operating margin growth has been spectacular.
6. ECM Weekly (22 Apr 2025) – Suzuki, Zenergy, Chagee, Duality, Manycore, Horizon, Giant Bio, TV Asahi
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, Duality Biotherapeutics delivered a strong listing, while Jiangsu Zenergy Battery Technologies was still holding on to its deal price.
- On the placements front, we looked at number of upcoming lockup expiries.
7. Waaree Energies IPO Lockup – Lots of Individual Shareholders Own over US$2bn Worth of Stock
- Waaree Energies (WAAREEEN IN) raised around US$514m in its India IPO in October 2024. The lockup on its pre-IPO investors is set to expire soon.
- Waaree Energies is a solar PV module manufacturer in India with an aggregate installed capacity of 12 GW, as of Jun 2024.
- In this note, we will talk about the lockup dynamics and possible placement.
8. Chagee Holdings – Thoughts on the IPO Debut and the Valuation Outlook
- Chagee may think that US IPO will help it gain greater imagination space/higher valuation. Although the tariff war is “a big surprise”, conservative IPO pricing still secure a good debut.
- If Chagee can successfully achieve internationalization and reverse the trend of declining performance, its market value could reach US$10.9 billion. However, Chinese concept stocks would still face valuation discounts.
- If same store GMV fails to stabilize, or overseas market penetration is lower-than-expected, or conflict between China and the US escalates, share price would face correction, with valuation falling below Starbucks.
9. Ather Energy IPO – Still Not Cheap Enough
- Ather Energy is now looking to raise about US$350m in its upcoming India IPO.
- Ather is a pure play electric vehicle company in India designing and developing E2Ws, battery packs, charging infrastructure, associated software and accessories, also manufacturing battery packs and assembling E2Ws in-house.
- In our previous note, we looked at the company’s past performance. In this note, we talk about the updates since then and valuations.
10. Wistron GDR Early Look – Riding the AI Server Boom Amid Macroeconomic Headwinds
- Wistron Corp (3231 TT) is looking to raise up to US$760m in its upcoming global depository receipts (GDRs) offering.
- On 2nd Apr 2025, Wistron announced that it had received its board’s approval to sell up to 250m common shares via a GDR offering.
- Similar to previous GDR listings, the deal is a long drawn out process with the firm required to jump through a number of board/shareholder/regulatory approval loops.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Chagee Holdings Limited (CHA): International Investors to Dominate the IPO Order Book
- Chagee’s order book is heavily influenced from Asian Investors as the deal is considered multiple-times oversubscribed.
- The underwriters and company came to market with a manageable size transaction and an attractive valuation.
- The geopolitical headwinds, specifically between China and the United States, is forcing many traditional IPO investors to stay on the sidelines.
2. Chagee Holdings (CHA US) IPO: Valuation Insights
- Chagee Holdings (CHA US), a leading premium tea drinks brand, is seeking to raise US$382-411 million through a Nasdaq IPO.
- We previously discussed the IPO in Chagee Holdings (CHA US) IPO: The Bull Case and Chagee Holdings (CHA US) IPO: The Bear Case.
- There are four cornerstone investors. Our valuation analysis suggests Chagee is attractively valued at the IPO price range. Therefore, we would participate in the IPO.
3. Chagee IPO: Is It Worth the Risks? Peer Comparison and Valuation Analysis.
- Chagee Holdings (CHA US) ‘s IPO valuation discount to its peers, including HK-listed tea-beverage players as well as US-listed China-based coffee-beverage player, suggest a strong potential upside on listing.
- US Investor concern over impact of tariffs and caution due to lingering memories of the Luckin Coffee scandal could translate to higher risk premium for the stock.
- Expect Chagee to trade at a discount to budget beverage peers like Mixue Group (2097 HK) given its limited room for network expansion within China and likely slower overseas growth.
4. Chagee IPO: Luckin X Starbucks of Tea. Pricing, Valuation, Key Facts & Financials
- Chagee Holdings (CHA US) is offering 14.68 million shares for USD26 to USD28 each to raise upto USD411 million in its initial public offering in the US.
- Chagee’s premium branded teahouses blend traditional tea culture with modern, tech-driven service, distinctly setting itself apart from bubble tea kiosks.
- Chagee’s IPO is priced at a discount to forward valuations of recently listed (in HK) China-based freshly brewed drinks players and leading Cafe companies.
5. Giant Biogene Placement – Great Track Record but Previous Deal Didn’t Do Well
- Giant Biogene (2367 HK) aims to raise up to US$250m via a top-up placement.
- We have followed the company since listing and its recent performance has been great. Although it doesn’t seem to need the cash and the previous deal didn’t go well.
- In this note, we will run the deal through our ECM framework and talk about the recent updates.
6. China Resources Beverage IPO Lockup- Cornerstones Coming Out of Lockup Ahead of the Large PE Release
- China Resources Beverage (2460 HK) raised around US$750m in its Hong Kong IPO in October 2024. The lockup on its cornerstone investors is set to expire soon.
- China Resources Beverage manufactures and sells packaged drinking water and RTD soft beverages in China and is one of the largest players in its categories.
- In this note, we will talk about the lockup dynamics and possible placement.
7. Pre-IPO Chagee Holdings – IPO Pricing Is Attractive, But Share Price May Underperform
- Chagee is seeking up to US$411 million by offering nearly 14.7 million ADS priced between US$26 and US$28 each, with market value to reach about US$4.8-US$5.1 billion.
- Chagee is facing performance headwinds. Whether the current high growth of Chagee is sustainable in the future is uncertain. This makes us tend to be conservative in Chagee’s valuation expectations
- Based on our forecast, P/E is about 11.5-12.3x if based on 2025 net profit. Such valuation is attractive, but “valuation discount” may occur due to market turmoil and geopolitical conflicts.
8. Rigaku IPO Lockup – Large PE Investors Can Still Break Even
- Rigaku Holdings (268A JP) raised around US$750m in its Japan IPO in October 2024. The lockup on its pre-IPO investors is set to expire soon.
- Rigaku engages in developing, manufacturing, sales and servicing scientific instruments specializing in X-ray technologies.
- In this note, we will talk about the lockup dynamics and possible placement.
9. ECM Weekly (14 Apr 2025) – Suzuki, EBOS, Hengrui Pharma, Zenergy, Chagee, LG India, Huge Dental
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, we looked at the possible A/H premium for Jiangsu Hengrui Medicine (600276 CH), along with two live deals in Hong Kong .
- On the placements front, only Suzuki Motor (7269 JP)‘s shareholders were brave enough to launch a placement in the turbulent markets.
10. Duality Biotherapeutics (映恩生物) Trading Update
- Duality Biotherapeutics raised HKD 1,512m (USD 194m) from its global offering and will list on the Hong Kong Stock Exchange on Tuesday, April 14th.
- In our previous note, we looked at the company’s business lines of ADC products and analyzed its valuation.
- In this note, we provide an update for the IPO before trading debut.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
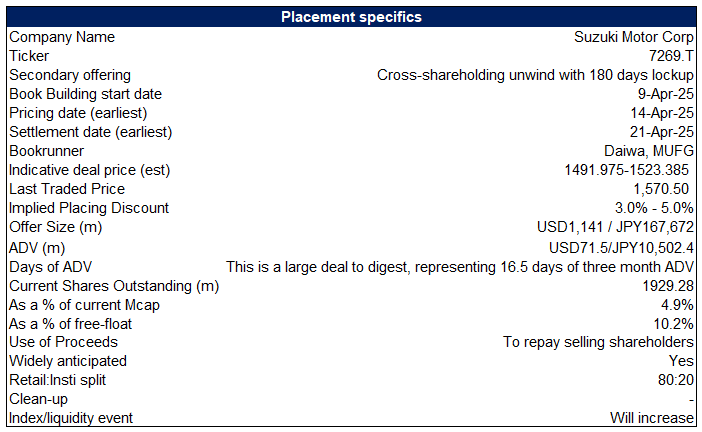
1. Suzuki Motor Placement – Not the Best Time for a US$1.15bn Deal. It Will Be a Long Week.
- Tokio Marine Holdings (8766 JP) and Sompo Holdings (8630 JP) aim to raise around US1.15bn (including over-allotment) via selling around 5% of Suzuki Motor (7269 JP).
- While Suzuki doesn’t have much direct exposure to the US markets, its shares have still corrected in line with other auto players.
- In this note, we will talk about the deal dynamics and run the deal through our ECM framework.
2. Suzuki Motor (7269 JP): A US$1.1 Billion Secondary Offering
- Suzuki Motor (7269 JP) has announced a secondary offering of up to 95.7 million shares (110.1 million including overallotment), worth around US$1.1 billion (US$1.3 billion including overallotment).
- Suzuki’s goal with the secondary offering is (i) to reduce cross-shareholdings and (ii) to expand and diversify the shareholder base, which should further enhance liquidity.
- Looking at recent large Japanese placements is instructive for understanding the potential offer price. The pricing date will fall between 21 and 23 April (likely 21 April).
3. Chagee IPO: Peer Comp and Thoughts on Valuation
- Chagee Holdings (CHA US) is planning to raise up to US$500m through its upcoming US IPO.
- It is a leading premium tea drinks brand, serving healthy and delicious freshly-made tea drinks.
- We have looked at the company’s past performance in our earlier notes. In this note, we discuss latest industry dynamics, conduct a quick peer comparison and discuss the company’s valuation.
4. Chagee Holdings (CHA US) IPO: The Bear Case
- Chagee Holdings (CHA US), a leading premium tea drinks brand, is seeking to raise US$400-500 million through a Nasdaq IPO.
- In Chagee Holdings (CHA US) IPO: The Bull Case, we highlighted the key elements of the bull case. In this note, we outline the bear case.
- The bear case rests on unsustainable growth rates, pressure on KPIs, signs of margin pressure, increasing S&M expenses and weakening forward growth indicators.
5. Key Takeaways from the Updated Filing on Hanwha Aero’s Rights Offering
- Hanwha shot down any merger talks between Hanwha Corp and Hanwha Energy, saying they’re just going to funnel Energy’s cash straight into Hanwha Aero via a third-party allotment.
- These confirm no price manipulation for Hanwha Corp; Hanwha Energy will inject cash into Aero at market value, likely driving bullish short-term price action for both Hanwha Corp and Aero.
- Despite tighter arb opportunities, doubts remain whether Hanwha Aero can raise the remaining KRW 1.6 trillion given a volatile market and the tight timeline.
6. Samsung SDI: Rights Offering Capital Raise Amount Lowered by 14% to 1.7 Trillion Won
- Samsung SDI (006400 KS) has lowered the rights offering capital raise amount by 14% to 1.7 trillion won, mainly due to the recent carnage in the global equity markets.
- The expected rights offering price has been lowered to 146,200 won, which is 14.9% lower than current price.
- We remain negative on Samsung SDI’s rights offering capital raise mainly due to shares dilution risk. We also remain concerned that the weak demand for EVs globally could last longer.
7. Hanwha Aerospace – Lowers Rights Offering Capital Raise Amount To 2.3 Trillion Won
- On 8 April, Hanwha Aerospace (012450 KS) announced that it plans to lower its rights offering capital raise amount from 3.6 trillion won to 2.3 trillion won (US$1.6 billion).
- The remaining 1.3 trillion won will be secured through a third-party allocation paid-in capital increase targeting three companies, including Hanwha Energy, Hanwha Impact Partners, and Hanwha Energy Singapore.
- Hanwha Aerospace disclosed today that it expects sales of 30 trillion won (58% higher than consensus) and operating profit of 3 trillion won (20% higher than consensus) in 2025.
8. Chagee Holdings IPO Valuation Analysis
- Our base case valuation of Chagee Holdings is target price of $46.7 per share, representing 67% higher than the high end of the IPO price range ($28 per share).
- Our base case valuation is based on a P/E of 21.4x on our estimated net profit of 2.9 billion RMB in 2025.
- We used a very conservative valuation multiple, mainly due to the extremely high macro risks related to the ongoing tariff dispute between China and the United States.
9. Duality Biotherapeutics (映恩生物) IPO: Valuation Upside at Risk
- Duality, a China-based clinical-stage biotechnology company, launched its IPO to raise up to US$200m via a Hong Kong listing.
- We look at the deal dynamics and latest developments in the biotech sector.
- The deal initially presented upside for investors but there’s a portion of its valuation now at risk due to the latest development.
10. Suzuki Motor (7269 JP): The Current Playbook
- Since the announcement of the US$1.1 billion secondary offering, Suzuki Motor (7269 JP)’s shares have remained broadly unchanged at the undisturbed price of JPY1570.5 per share (7 April).
- It is instructive to look at recent large Japanese placements to understand the potential trading pattern. Suzuki’s share performance is the joint best among recent large placements.
- However, the shares have underperformed the Nikkei 225 index (up 7.9%). The offering will likely be priced on 14 April. The average large Japanese placement tends to generate positive returns.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. CATL A/H Listing – Thoughts on A/H Premium
- Contemporary Amperex Technology (CATL) (300750 CH), one of the world’s largest battery solutions providers, aims to raise at least US$5bn in its H-share listing.
- CATL is the global leader in new energy vehicle battery solutions, in China and globally, as per SNE Research. Its A-shares have been listed since 2018.
- We have looked at the company’s past performance in our earlier notes. In this note, we talk about its recent updates and provide our thoughts on valuations.
2. ECM Weekly (31st Mar 2025) – Xiaomi, NIO, FCT, Gigabyte, DN Sol, Nanshan Al, Zenergy, LXJ, Veeda
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, DN Solutions (298440 KS)‘s range looks a little pricey, while Eco-Shop Marketing (ECO MY) could trade ahead of its listed peers, in our view.
- On the placements front, Xiaomi Corp (1810 HK) matched BYD (1211 HK) in size, but couldn’t do so in returns.
3. Chagee Holdings (CHA US) IPO: The Bull Case
- Chagee Holdings (CHA US), a leading premium tea drinks brand, is seeking to raise US$400-500 million through a Nasdaq IPO.
- According to iResearch, as of December 31, 2024, Chagee was the largest premium freshly made tea drink brand in China by the number of stores.
- The bull case rests on a strong brand, leading market share, peer-leading revenue growth, top-tier profitability and cash generation.
4. Wuxi XDC Placement – Following Biologics Playbook, past Deals Have Been Mixed
- WuXi AppTec (2359 HK) aims to raise around US$250m via selling around 3.5% stake in WuXi XDC Cayman (2268 HK).
- WuXi XDC Cayman (WXDC) is a contract research, development, and manufacturing organization (CRDMO) focused on the global antibody drug conjugates (ADC) and broader bioconjugate market providing integrated and end-to-end services.
- In this note, we will talk about the placement and run the deal through our ECM framework.
5. Chagee Holdings Limited (CHA): Peeking at the IPO Prospectus of China’s Premium Tea Brand
- As of December 31, 2024, their network comprised 6,440 teahouses, including 6,284 located in China.
- Their net revenues increased by 844% to RMB4,640.2 million in 2023 from RMB491.7 million in 2022.
- We anticipate this company to set terms (share size, price range) and debut in the second half of April.
6. Duality Biotherapeutics (映恩生物) Pre-IPO: Valuation and the Trap
- Duality Biotherapeutics, a China-based clinical-stage biotechnology company, plans to raise up to US$250m via a Hong Kong listing.
- We look at the company’s valuation based on its core products, namely DB-1303, DB-1311, and DB-1305.
- We highlight key differences between our valuation and the broker valuation guidance.
7. Clearing up FSS Review of Samsung SDI & Hanwha Aerospace: Watch for Ramped-Up Recall Pressure
- Samsung SDI’s rights offering is locked in and even accelerated. Hanwha Aerospace awaits FSS approval, but a pullback is unlikely, with no major red flags seen by regulators.
- With a four-week gap, supply pressure eases, reducing overhang concerns. This shift in dynamics impacts stock rights pricing and is key for any arb setup.
- The wider schedule gap between deals boosts lenders’ flexibility, increasing the likelihood of a stronger share recall. This makes for a solid trade setup, targeting recall-driven price action.
8. Chagee Pre-IPO – Market Leading Growth but Showing Signs of Fatigue
- Chagee Holdings (CHA US) is planning to raise up to US$500m through its upcoming US IPO.
- Chagee is a leading premium tea drinks brand, serving healthy and delicious freshly-made tea drinks.
- In this note, we look at the firm’s past performance.
9. SmartStop Self Storage (SMA): IPO for Yield Chasers, Traditional Players on the Sidelines
- According to our sources, the deal is multiple-times oversubscribed — our sources stated around 5x.
- Self-Storage was Monday’s second best performing sub-sector (+1.8%) as the overall REIT sector (+0.7%) slightly outperformed the broader market.
- While the “typical” IPO investor may not be “enthused”, the timing for this type of deal “may” be ideal for yield-chasers.
10. Maynilad Water Services Pre-IPO – The Positives – Key Infrastructure Provider
- Maynilad Water Services (MYNLD PH) (MWS) is looking to raise at least US$633m in its upcoming Philippines IPO.
- MWS is a leading global water utility player operating the largest concession by population served within a single concession area in the Philippines and Southeast Asia (SEA), as per GlobalData.
- In this note, we talk about the positive aspects of the deal.